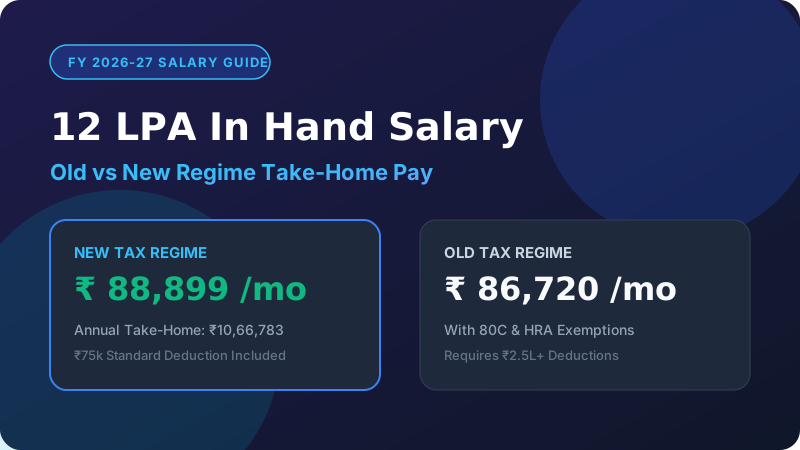
12 LPA In Hand Salary: Monthly Take-Home Under Old and New Tax Regime
Complete ₹12 Lakhs CTC calculation for FY 2026-27. Compare New vs Old regime, PF options, professional tax, and exact monthly in-hand take-home.
No vague generalities, no robotic filler. Every article is written with real numbers, verified against FY 2026-27 tax rules, and designed to help you decode your salary slip and make confident financial decisions.
Try a different search term or click "All Guides" to view the full library.
Complete ₹12 Lakhs CTC calculation for FY 2026-27. Compare New vs Old regime, PF options, professional tax, and exact monthly in-hand take-home.
Discover your real net monthly take-home on a 10 LPA CTC offer. See statutory EPF deductions, slab-wise tax calculations, and how to optimize your salary slip.
Why 8 LPA leaves ₹58,000 to ₹61,000 monthly take-home. Explore the ₹75,000 standard deduction, marginal tax relief, and EPF calculation nuances.
Cross the ₹90,000 to ₹97,000 monthly barrier. Detailed analysis of 20% tax slab, capped vs uncapped PF, and real CTC structure secrets.
High earner payroll roadmap. Stepping into the 30% tax bracket, breakeven math between Old vs New tax regimes, and maximizing net wealth.
Demystifying CTC components: employer PF, gratuity accrual, group medical insurance, performance bonuses, and why offer letters mislead freshers.
Step-by-step breakeven analysis for FY 2026-27. Calculate exactly how many deductions you need before the Old Regime beats the New Regime.
Tactical tips for Indian professionals. How to identify inflated CTC figures, negotiate for higher fixed pay, and ask for optimal allowance splits.
Decode every line item on your monthly paystub. Why companies keep basic salary at 40-50%, what special allowance really is, and statutory limits.
Master HRA exemption calculation under Section 10(13A). Learn the 3-condition rule, metro vs non-metro limits, and paying rent to parents legally.
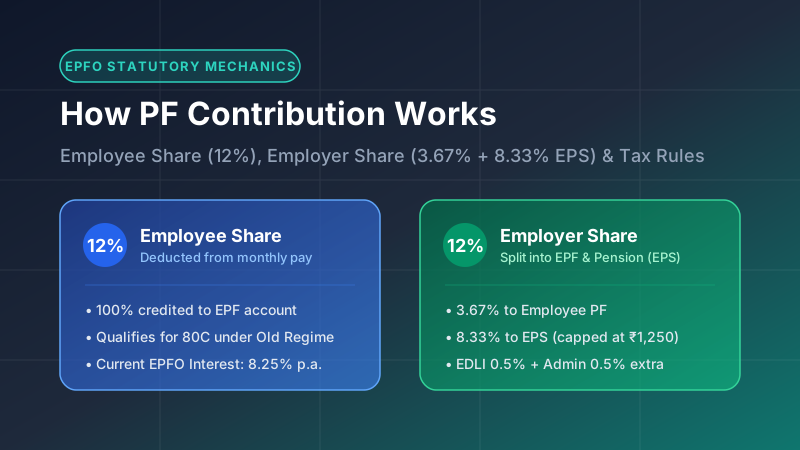
Understand the 12% calculation formula, the ₹1,250 monthly EPS ceiling, statutory wage limits, and 8.25% interest compounding rules.
The statutory 15/26 formula under the Payment of Gratuity Act 1972, the 4 years 240 days continuous service precedent, and ₹20 Lakh tax relief.
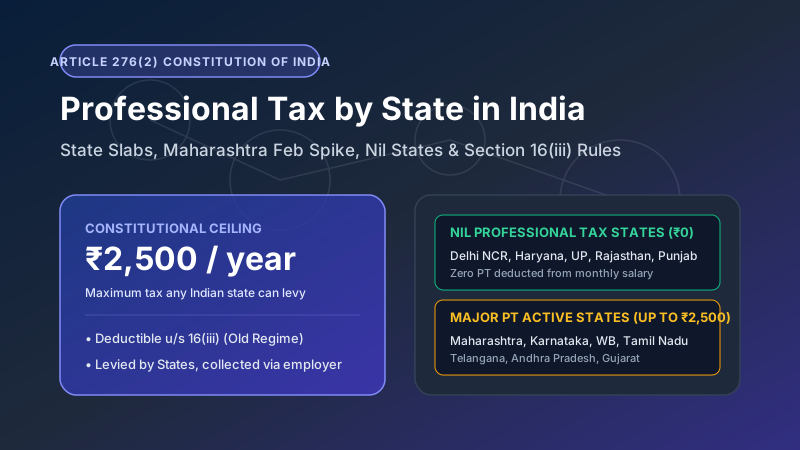
State rate charts for FY 2026-27. Compare Maharashtra's ₹300 Feb spike, Karnataka, Tamil Nadu, and Nil PT states like Delhi, Gurgaon, and Noida.
Master the 4 core formulas, mental math hacks like X% of Y = Y% of X, fraction-to-decimal matrix, and real-life shopping, exam, and GST calculations.
Relative growth formulas, decimal multipliers, why a 50% drop requires a 100% gain to recover, and percentage points vs percentage change.
Learn exact formulas for CTC vs in-hand increment, variable pay traps, joining bonuses, inflation adjustments, and counter-offer evaluations.
Master forward vs reverse GST math, CGST/SGST vs IGST splits, reverse charge mechanism (RCM), input tax credit (ITC), and invoice verification.
Successive discounts demystified (50% + 50% != 100%), Buy 2 Get 1 real savings, cashback vs instant discounts, and mental shortcuts for sale events.
Why a 25% markup is only a 20% margin, conversion conversion formulas, gross vs net margin, pricing pitfalls, and healthy Indian business benchmarks.
Reducing balance math, why early loan payments are 80%+ interest, how an extra EMI/year cuts tenure by 5+ years, and home vs car loan strategies.
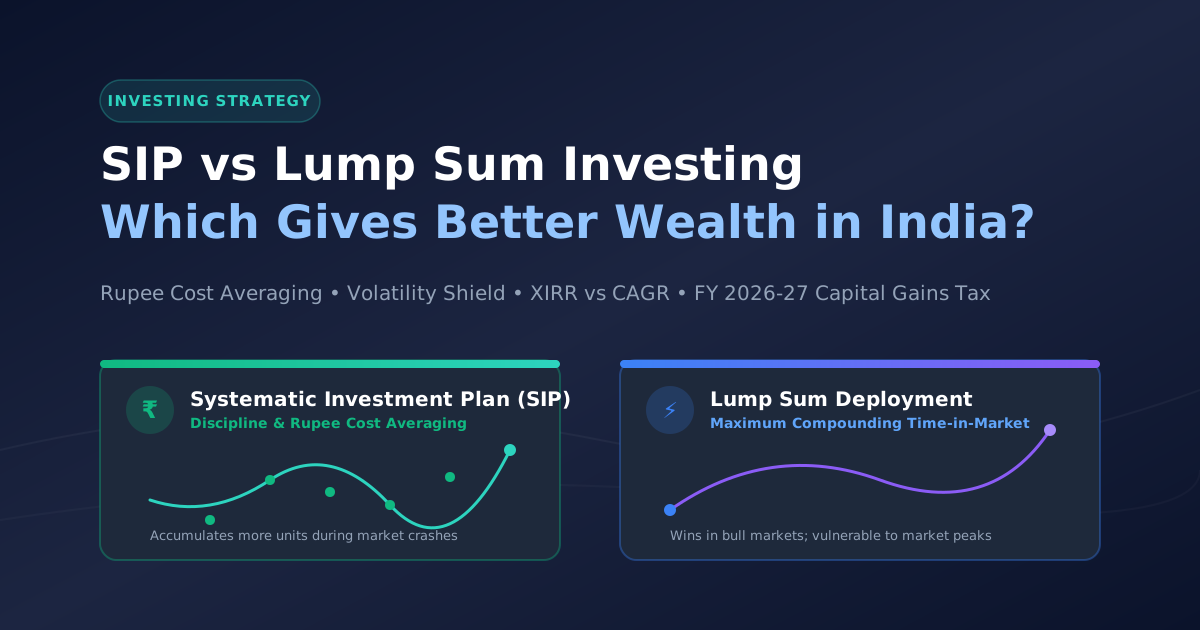
Rupee Cost Averaging, market timing fallacies, 12-month FIFO capital gains tax rules, XIRR vs CAGR math, and 10% Step-Up SIP simulations.
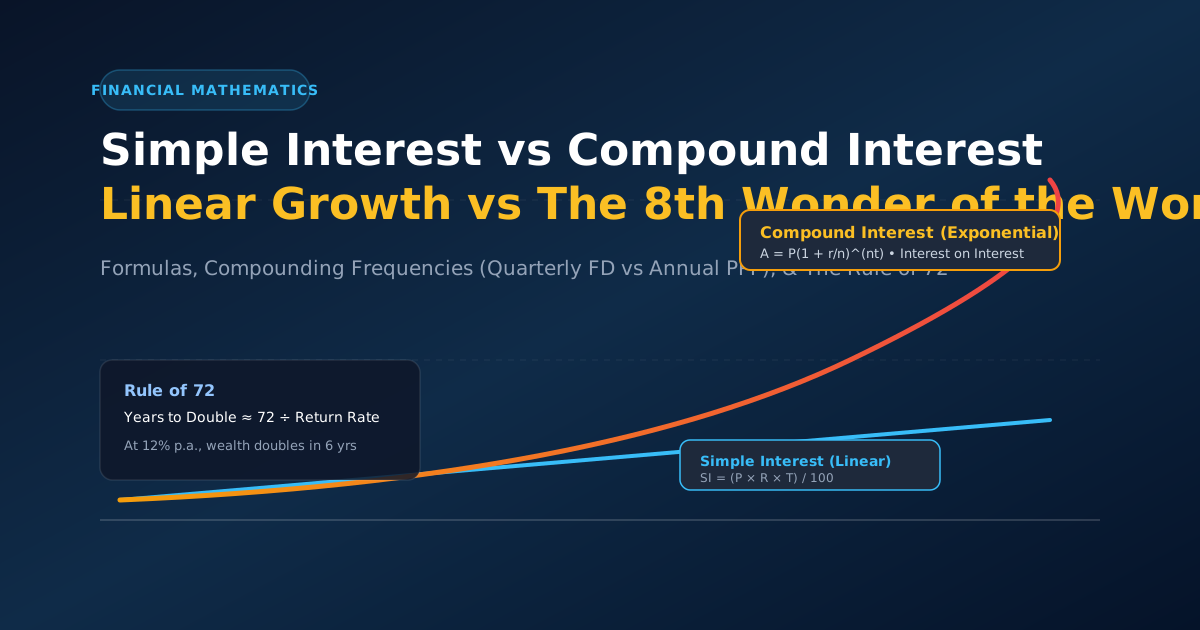
Quarterly FD compounding, PPF 5th of month rule, the Rule of 72 derivation, 30-year wealth models, and toxic credit card APR daily compounding.
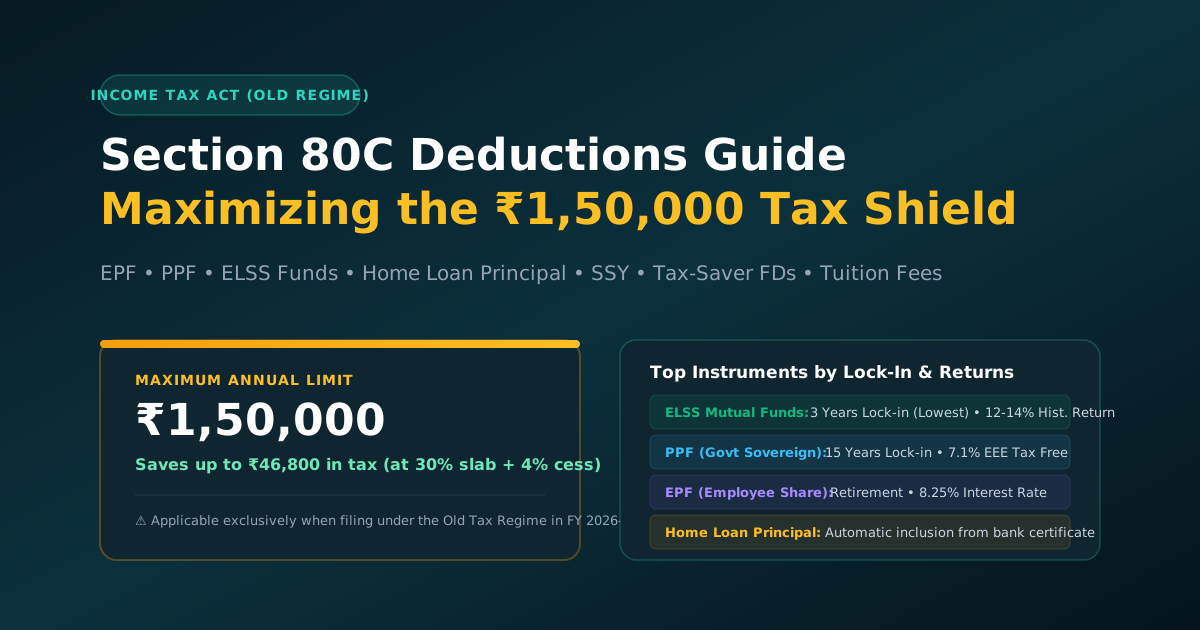
Max out the ₹1.5L tax shield. Compare ELSS, PPF, EPF, SSY, home loan principal, tuition fees, and learn why 80C is Old Regime exclusive.
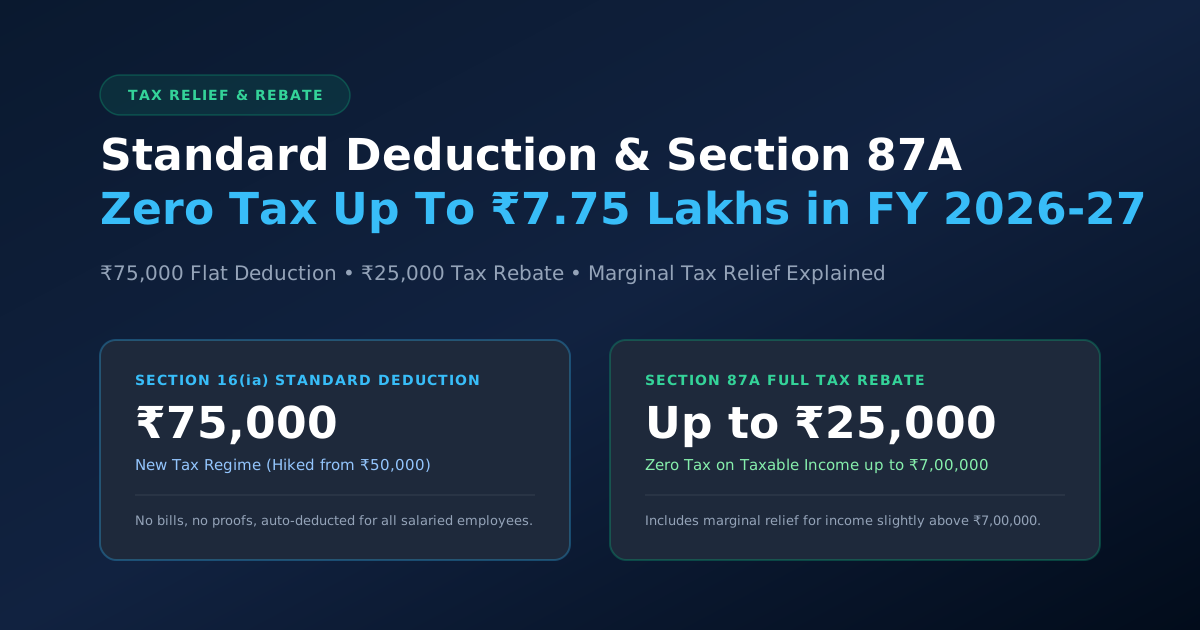
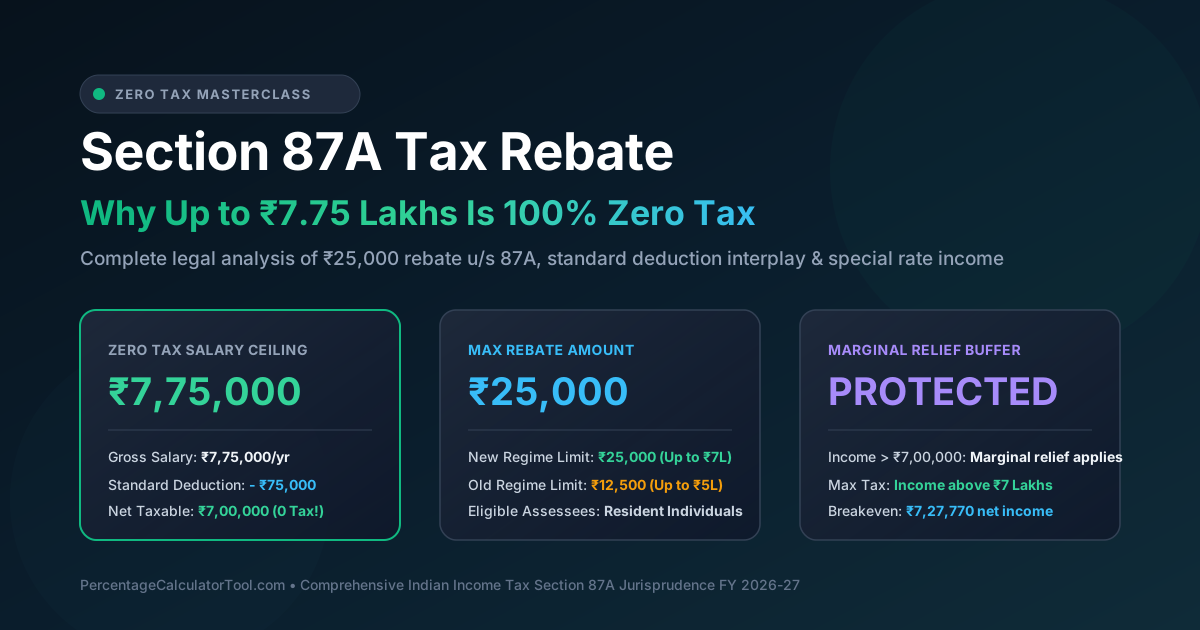
How ₹7.75 Lakhs gross salary becomes ₹0 tax under the New Regime. Explore the ₹75,000 standard deduction, ₹25,000 rebate, and marginal relief math.
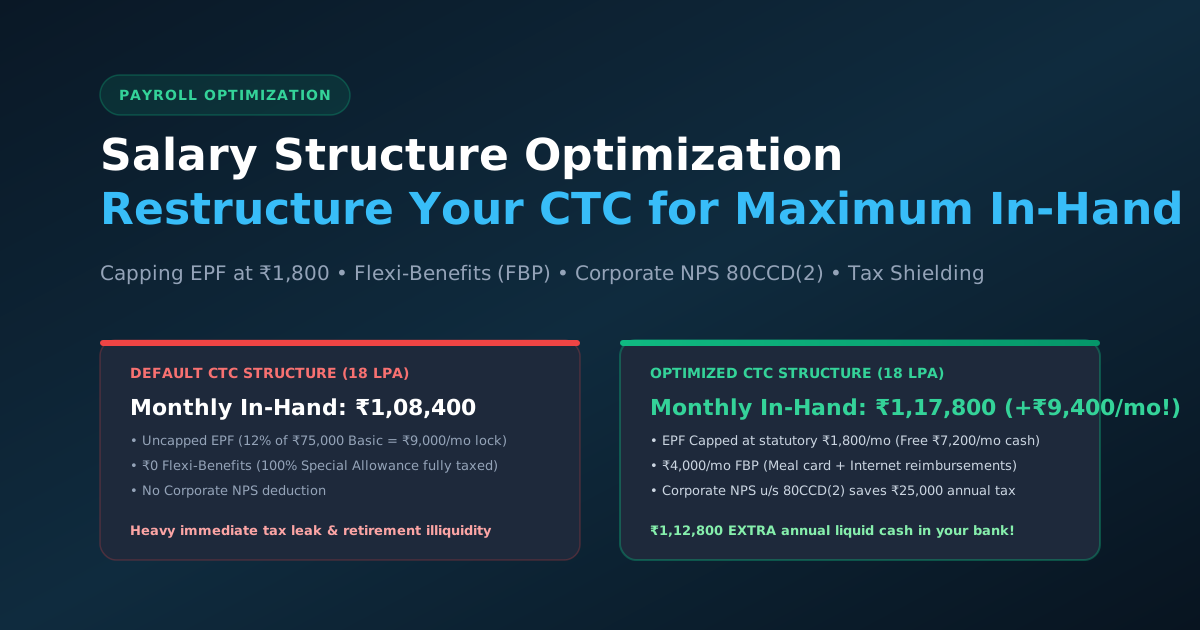
Surge your monthly take-home by ₹8,000+. Learn EPF capping at ₹1,800, Corporate NPS 80CCD(2), meal vouchers, and car lease perquisites.
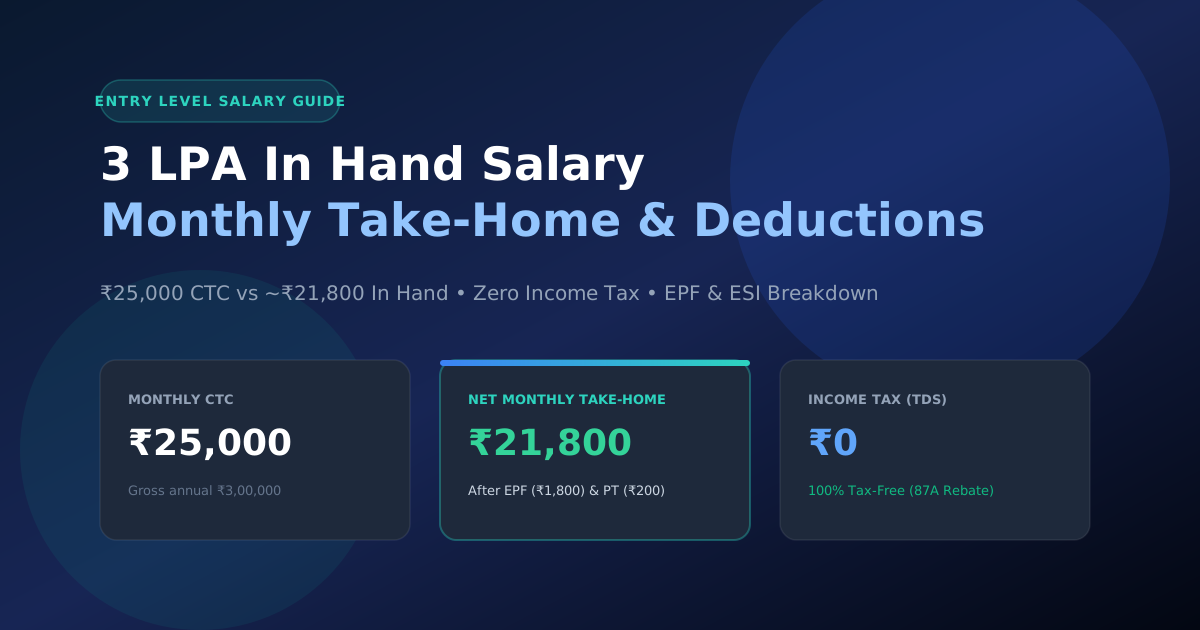
Why ₹25,000 CTC yields ~₹21,800 in hand. Complete statutory EPF, ESI ₹21,000 threshold rules, zero income tax, and city living budgets.
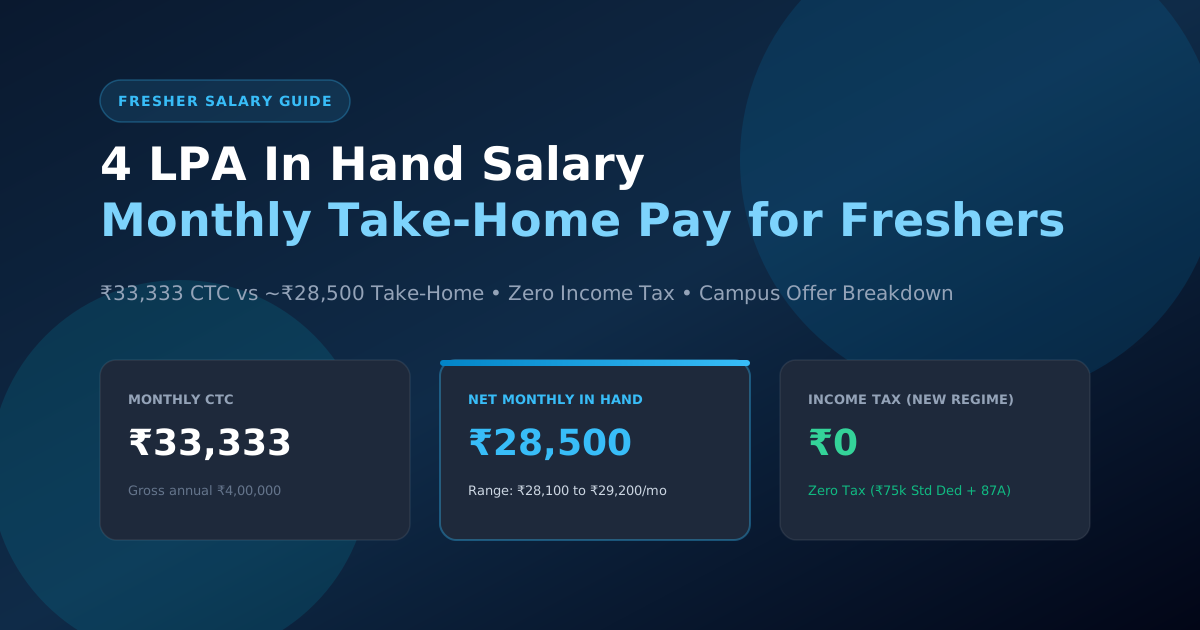
Itemized paystub split from ₹33,333 CTC to ~₹28,500 take-home. 3 campus offer structures, capped vs uncapped EPF, and zero tax proof.
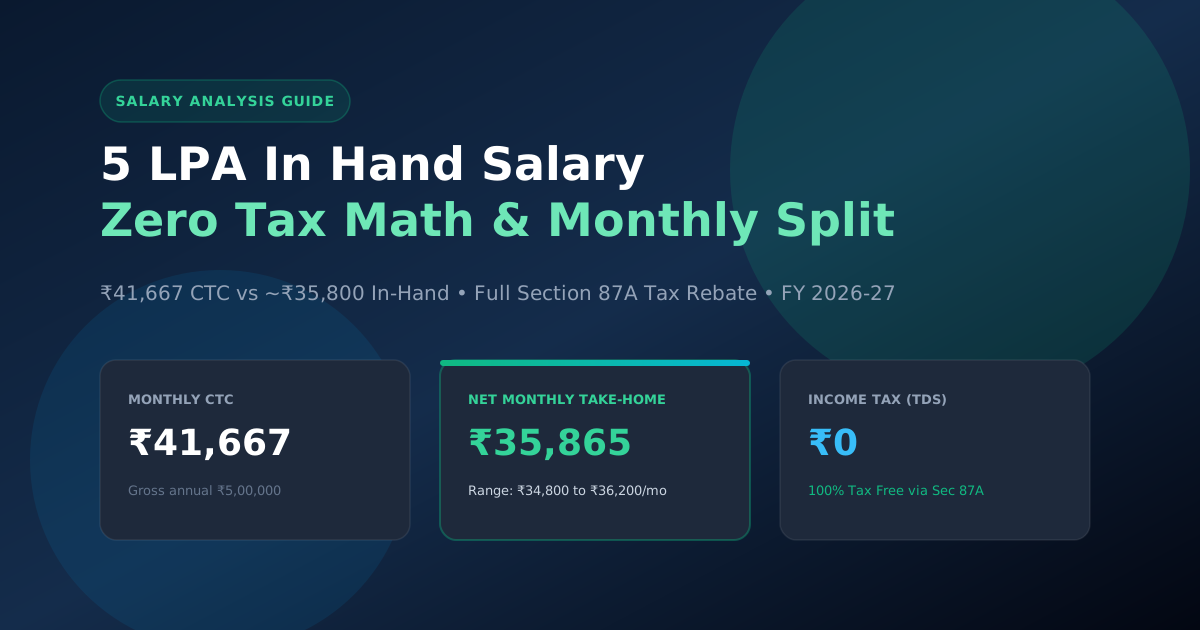
Exact monthly breakdown from ₹41,667 CTC to ~₹35,865 in hand. Section 87A rebate proof, capped PF benefits, and wealth budgeting.
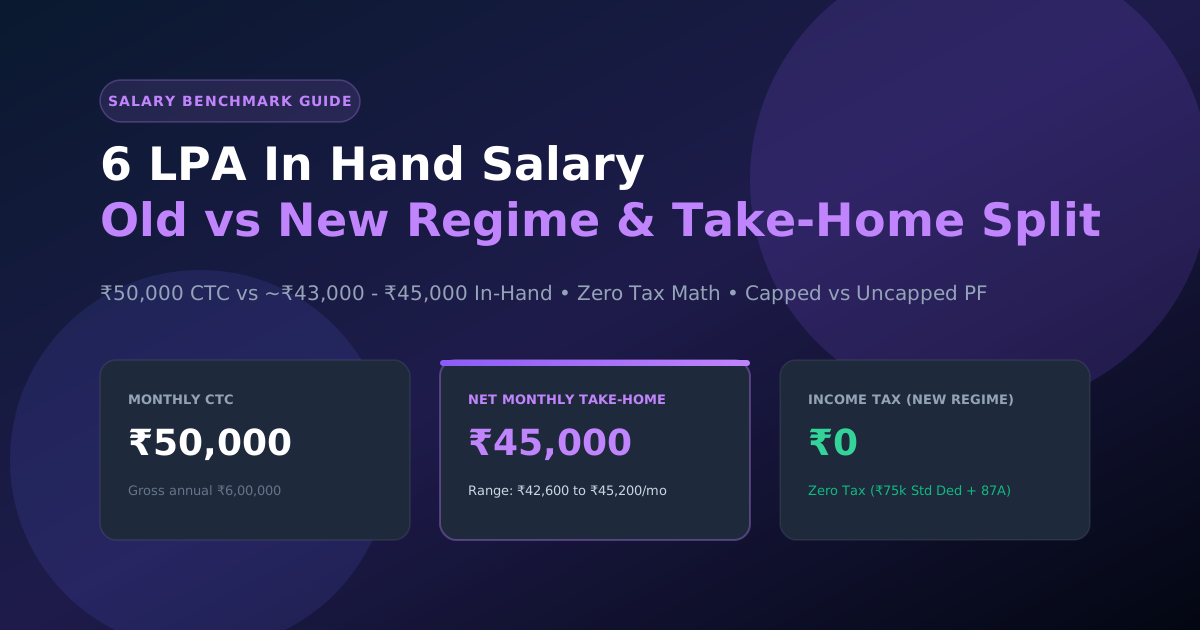
Why ₹50,000 CTC yields ~₹45,000 take-home. Detailed tax regime comparison, EPF capped vs uncapped compounding, and gratuity math.
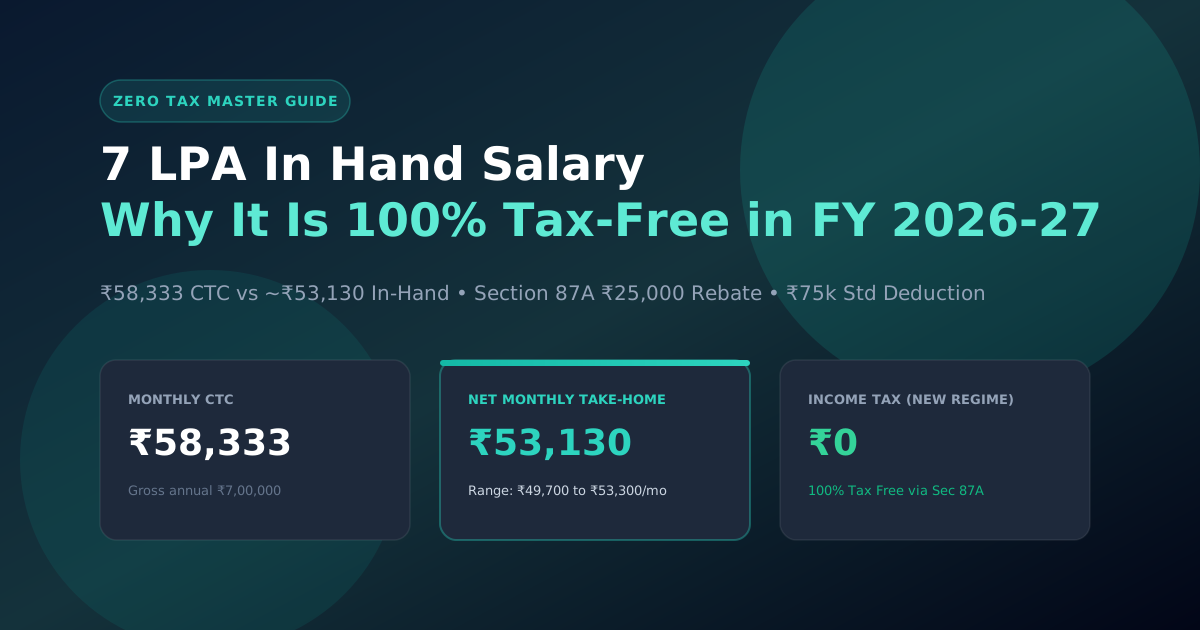
From ₹58,333 CTC to ~₹53,130 in-hand. Explore the Section 87A rebate proof, the ₹7.75 LPA maximum zero-tax shield, and the 8 LPA tax cliff.
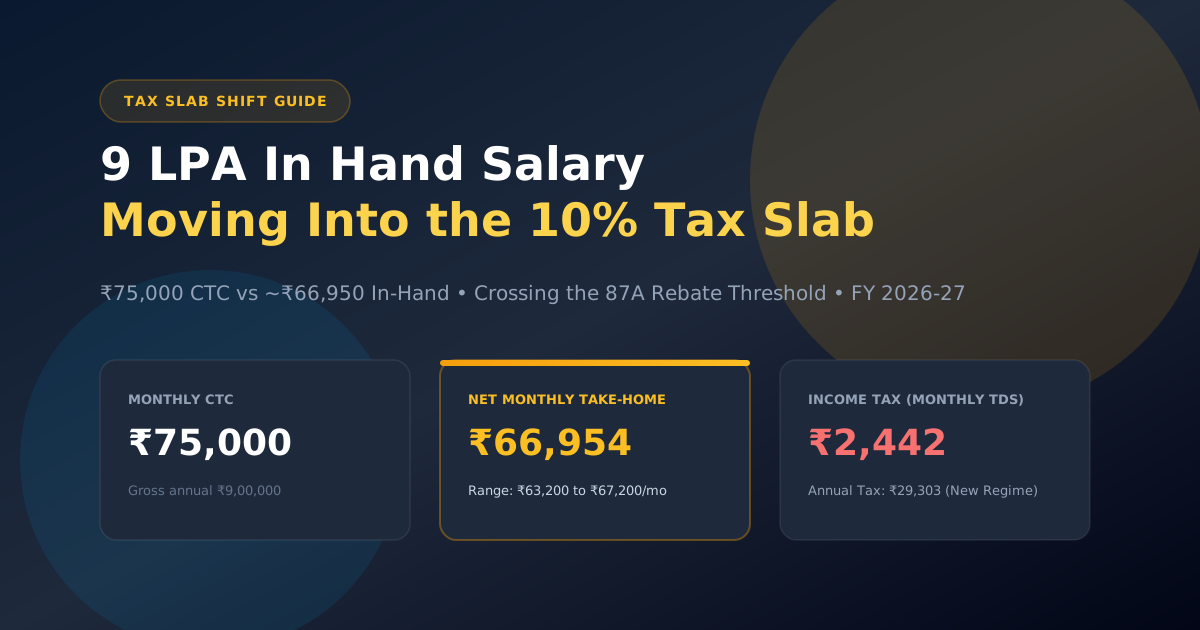
From ₹75,000 CTC to ~₹66,954 take-home. Crossing the Section 87A rebate ceiling, exact 10% slab tax, and New vs Old regime math.
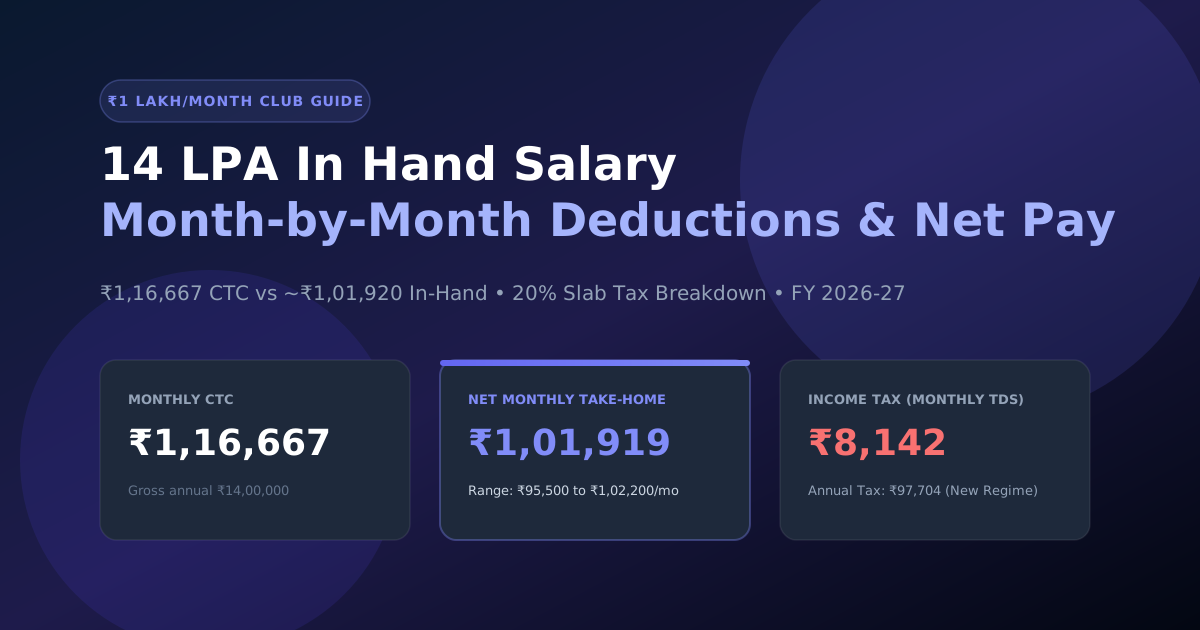
Crossing into six-figure monthly take-home at ₹1,01,919. 20% slab tax decomposition and why New Regime beats Old Regime by ₹64,000+.
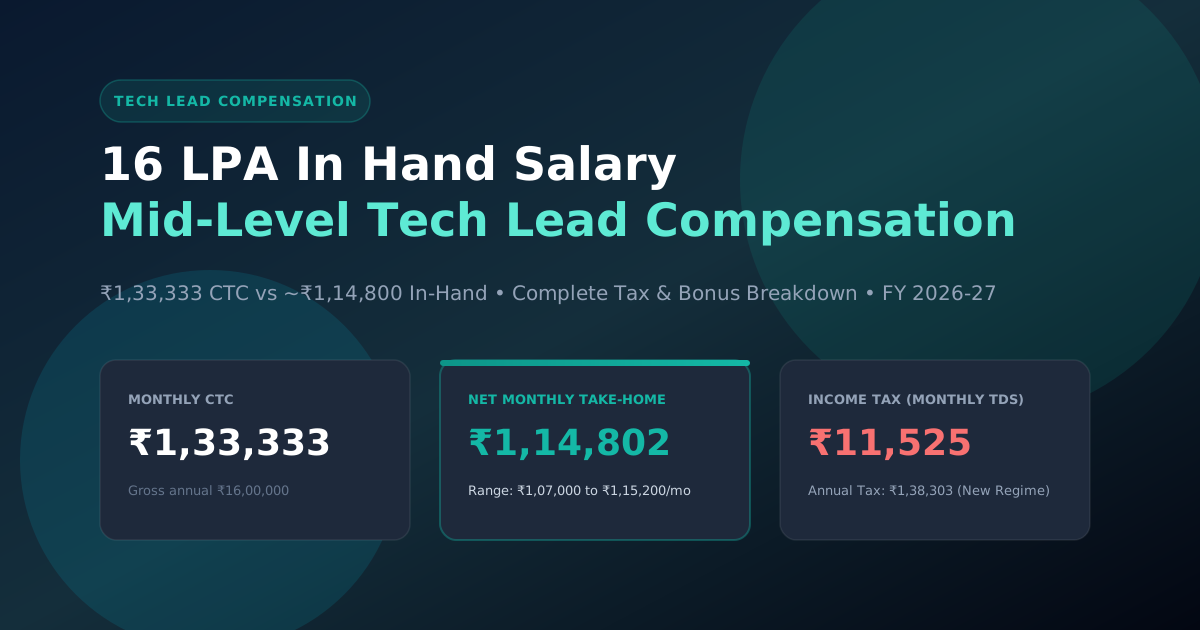
From ₹1,33,333 CTC to ~₹1,14,802 take-home. 3 tech lead offer models, 20% slab tax, and Corporate NPS Section 80CCD(2) optimization.
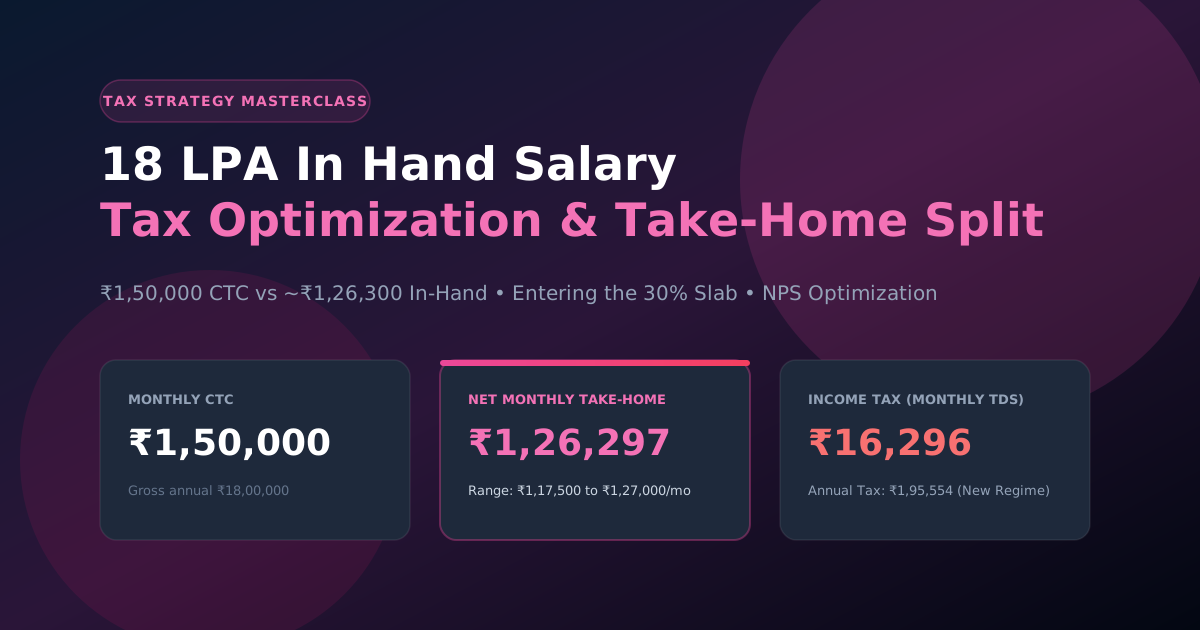
Entering the 30% tax bracket with ~₹1,26,297 in-hand. Learn how Corporate NPS and EV lease perquisites save ₹65,000+ in taxes legally.
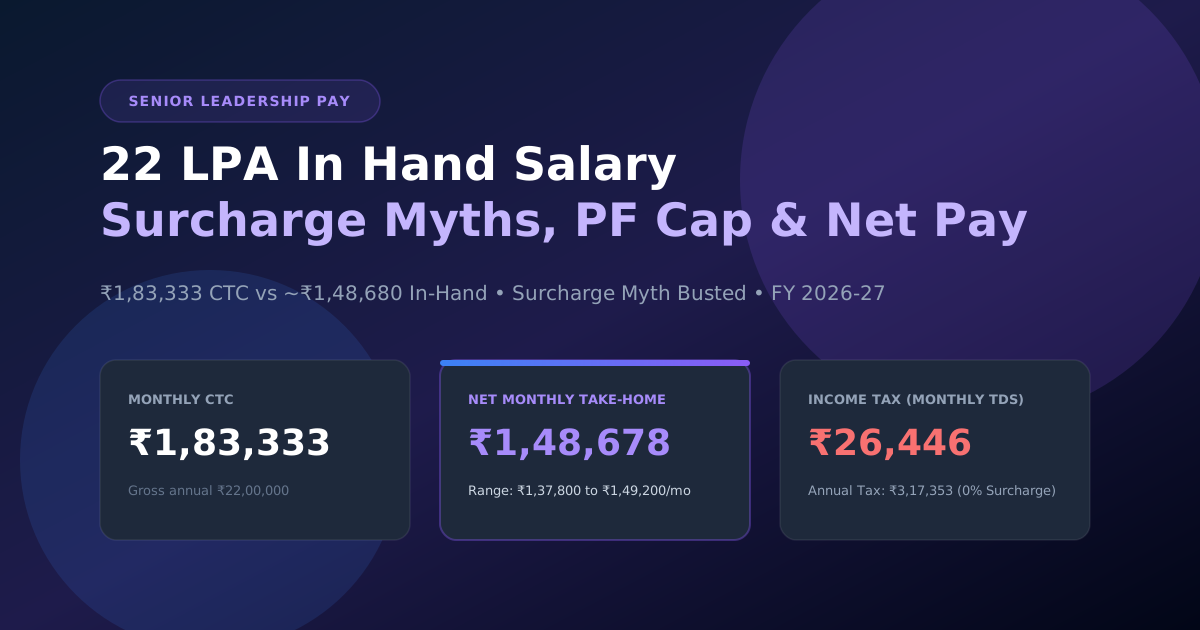
From ₹1,83,333 CTC to ~₹1,48,678 in-hand. Busted surcharge myths (0% rate under ₹50L), PF capping benefits, and 30% slab calculations.
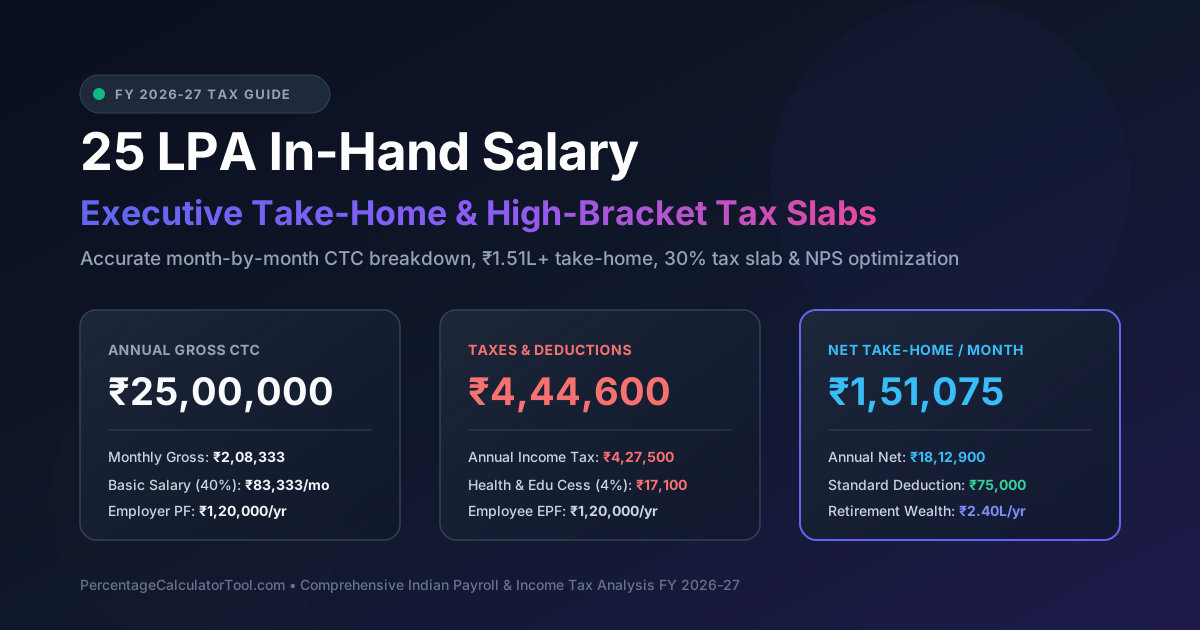
From ₹2,08,333 CTC to ₹1,51,075 take-home. 30% tax bracket breakdown, Corporate NPS tax shields, and regime breakeven math.
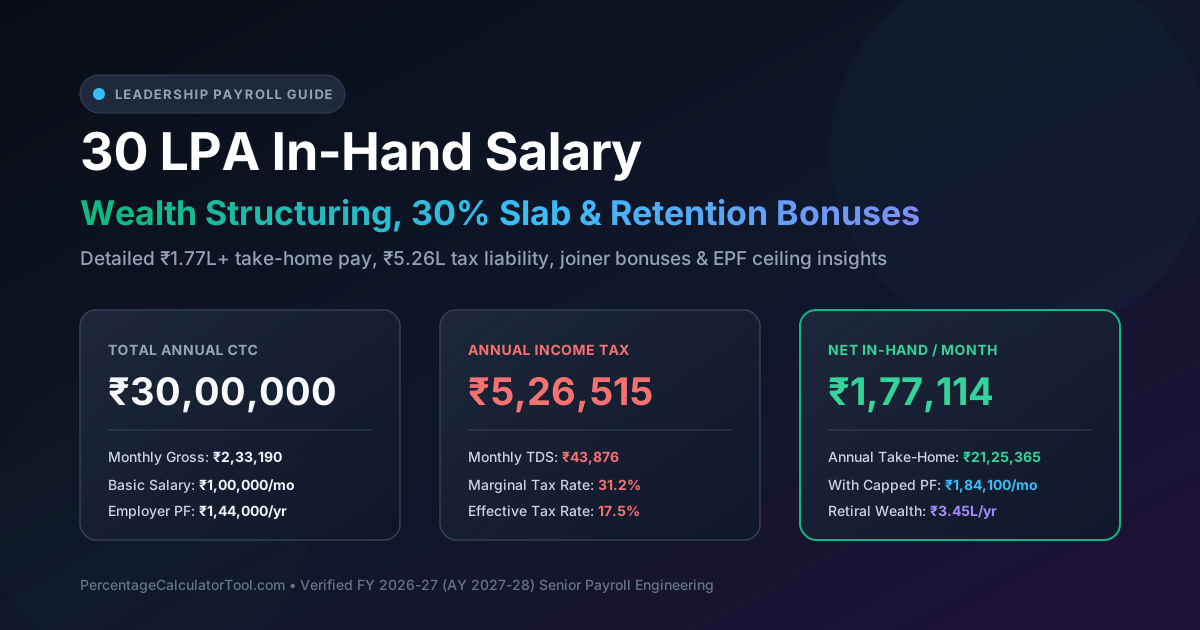
From ₹2.50L monthly CTC to ₹1.77L+ in-hand. Signing bonus 31.2% TDS clawback rules, car lease benefits, and capped PF liquidity.
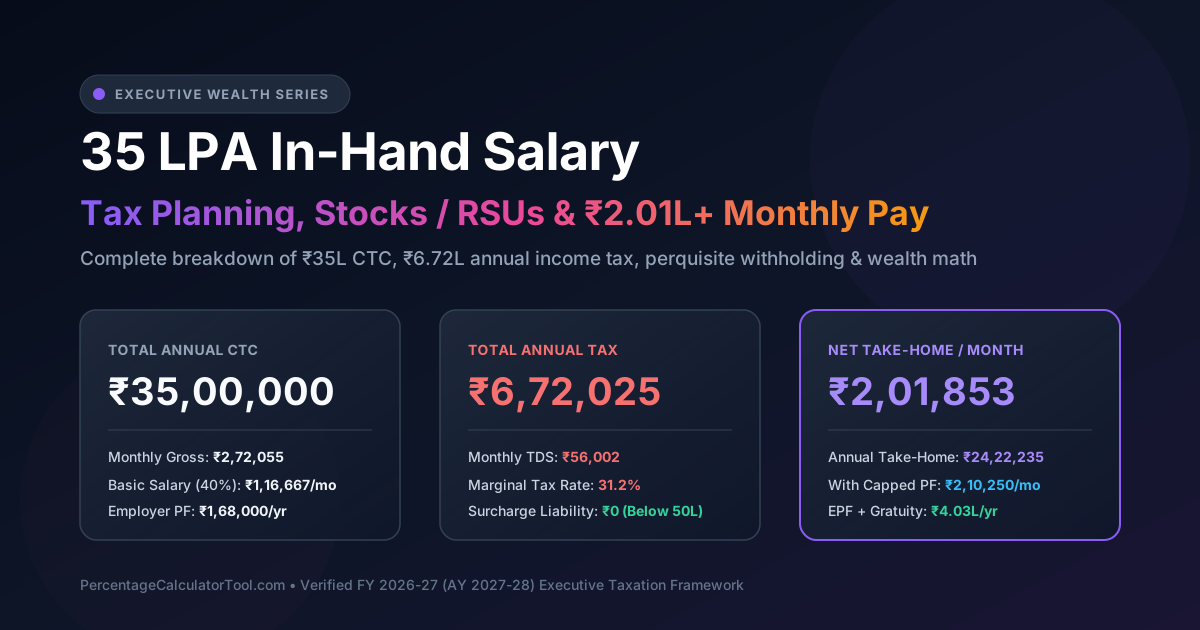
Crossing the ₹2 Lakh monthly take-home mark. RSU perquisite taxation, Schedule FA foreign asset disclosure, and 31.2% tax math.
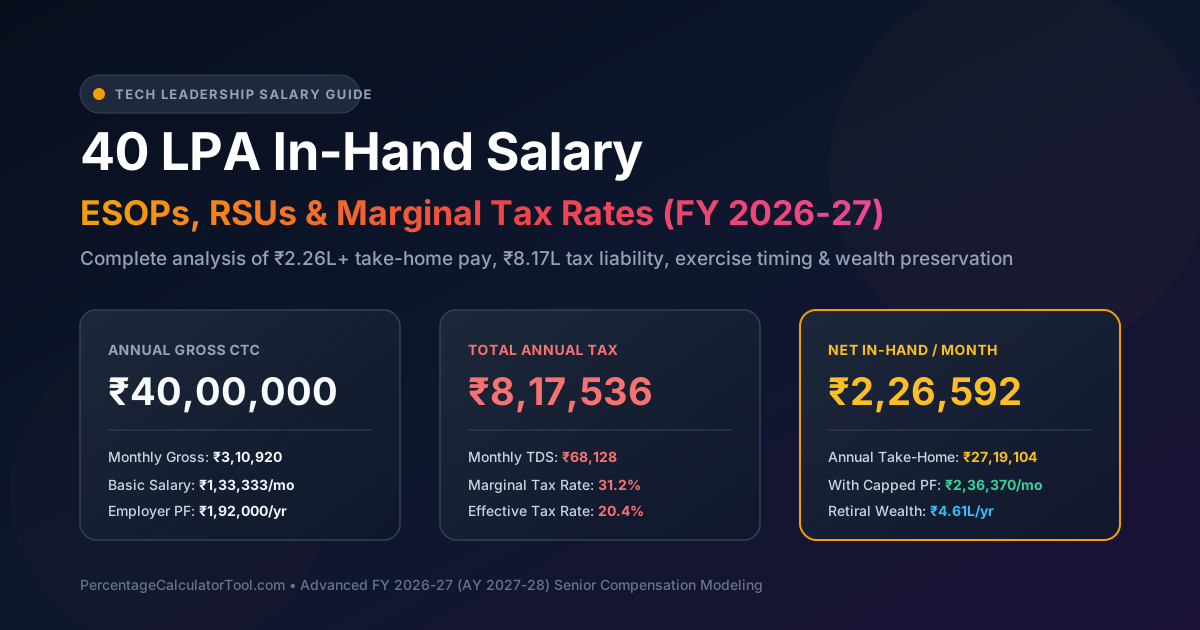
From ₹3.33L CTC to ₹2.26L+ take-home. Unlisted startup ESOP exercise risk, Section 80-IAC tax deferral, and cashless exercises.
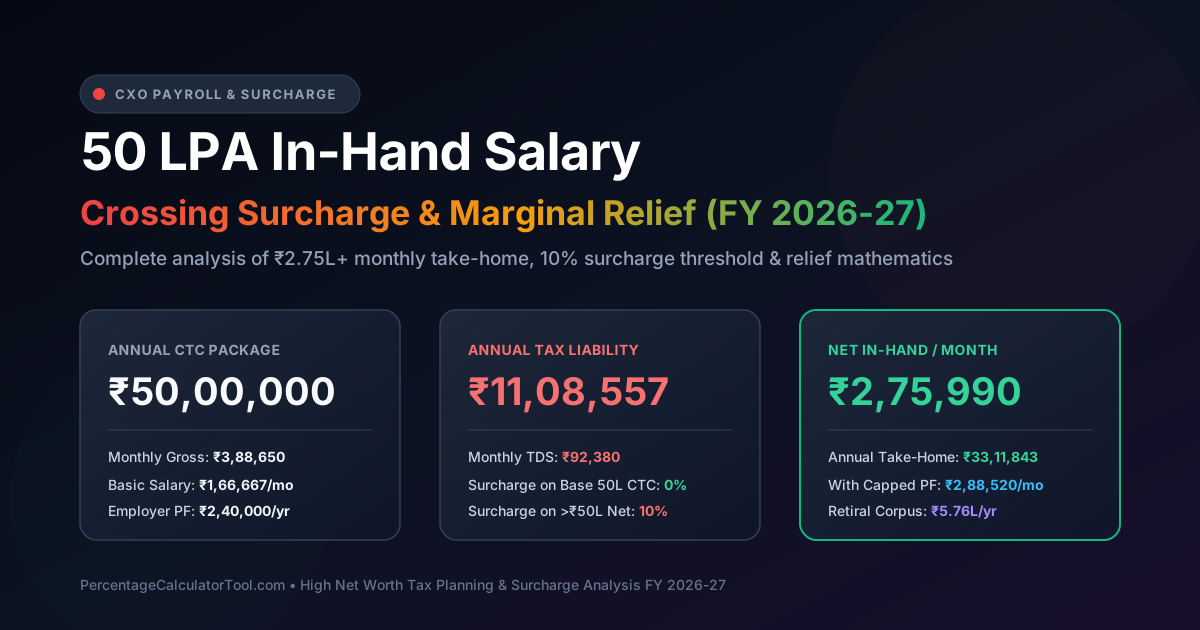
Half-crore payroll math: ₹2.75L+ take-home pay, 10% surcharge mechanics, and step-by-step Marginal Relief formula under Section 115BAC.
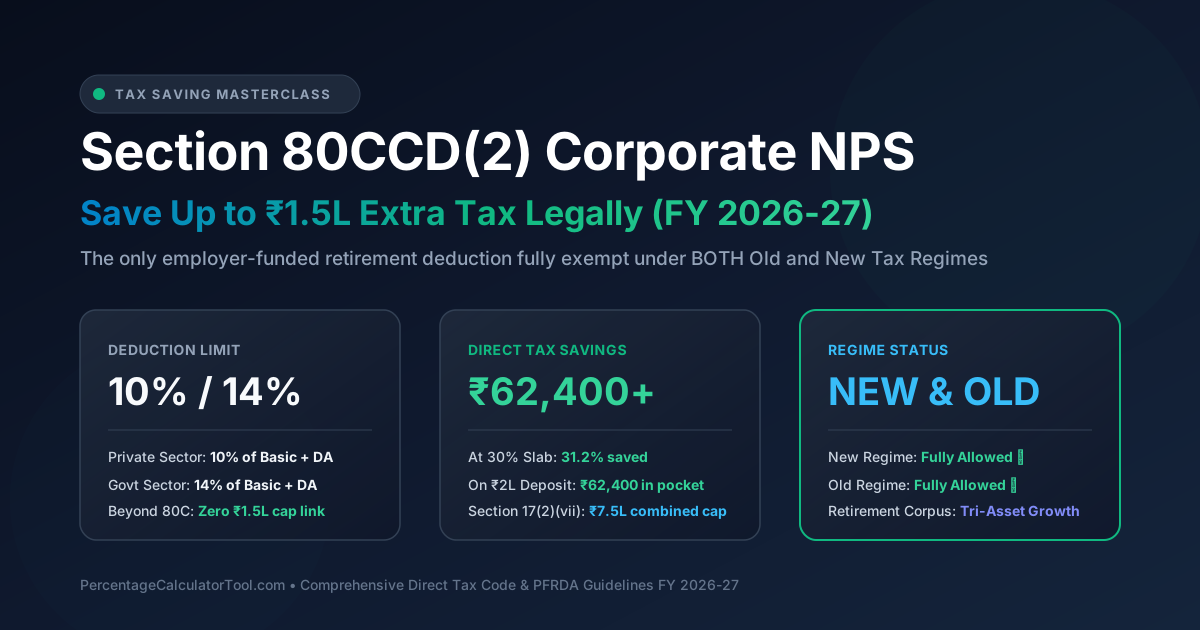
The ultimate tax shelter. Why employer NPS contributions remain 100% tax-exempt under BOTH Old and New regimes, saving up to ₹62,400+ in tax.
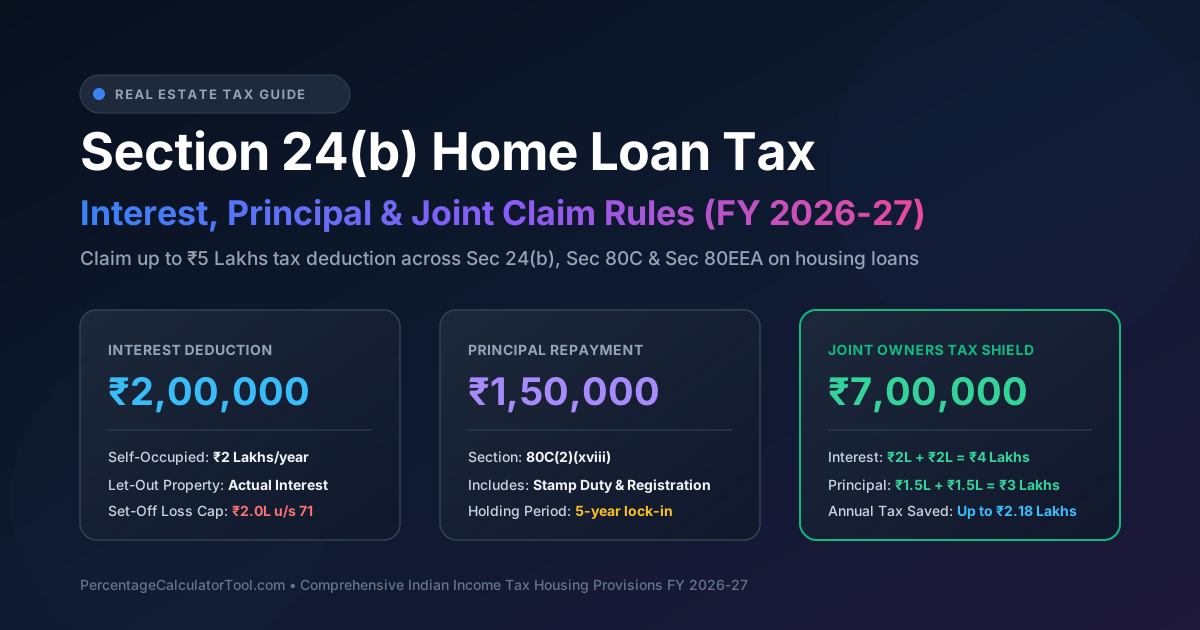
Claim up to ₹7 Lakhs deduction jointly with spouse. Section 24(b) ₹2L interest rules, pre-construction 5-year tranches, and 80C stamp duty.
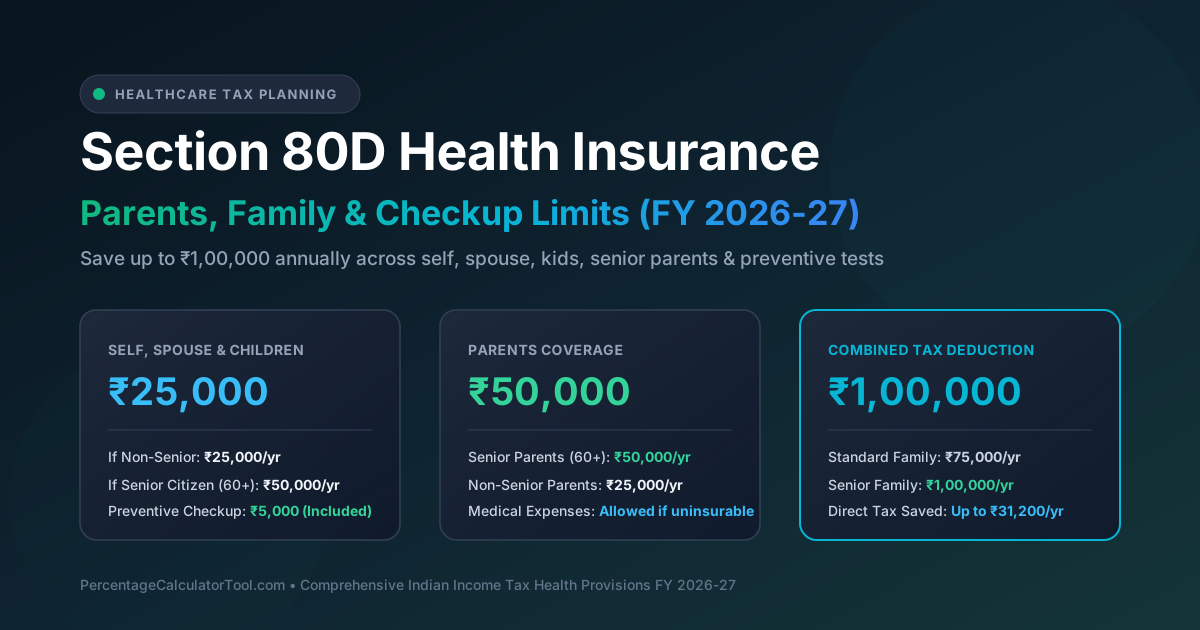
Save up to ₹1,00,000 annually. Senior parent medical bills up to ₹50k without insurance, ₹5,000 cash preventive checkups, and multi-year policy rules.
Complete guide to the new regime: 12.5% LTCG, 20% STCG, ₹1.25L exemption, pre-July 2024 property grandfathering, and tax-loss harvesting.
Step-by-step e-filing manual. Reconcile Form 16 with AIS/TIS and 26AS, report foreign stocks (Schedule FA), avoid defective notices, and e-verify.
Master Section 87A tax rebate for FY 2026-27. Understand the ₹25,000 rebate limits, ₹7.75 LPA zero-tax threshold, and marginal relief formulas.
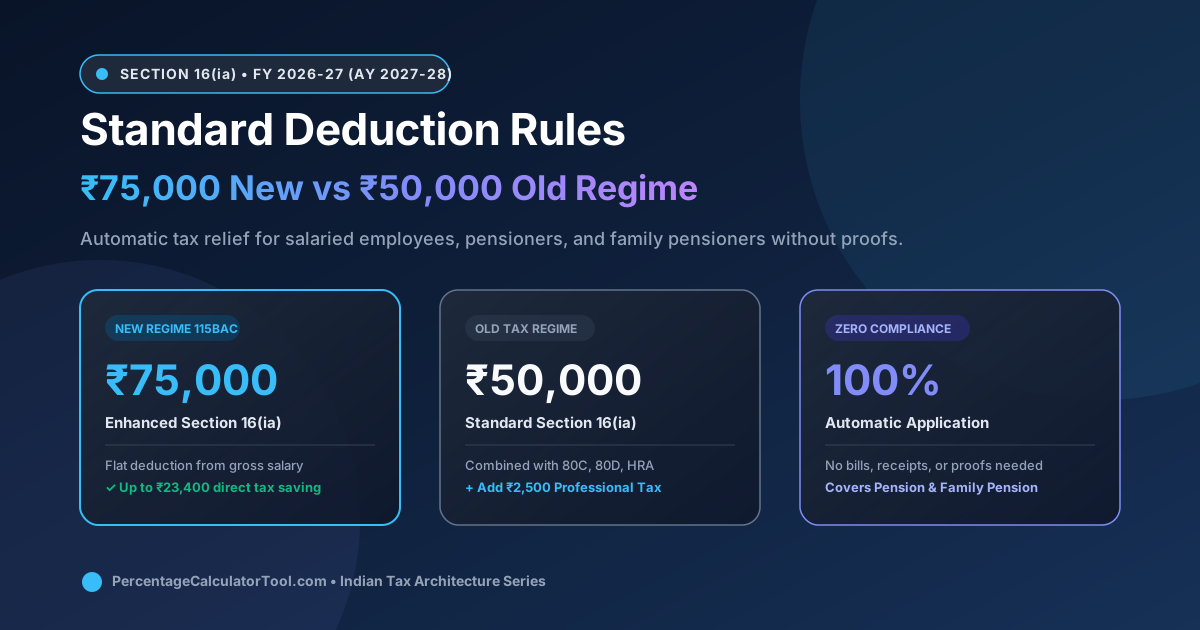
Section 16(ia) rules for salaried employees and pensioners. Exact tax savings across slabs and how to prevent dual employer double counting.
Complete guide to Section 208 pay-as-you-earn rules. 15th June/Sept/Dec/Mar installment schedules, safe harbors for capital gains, and e-Pay Tax steps.
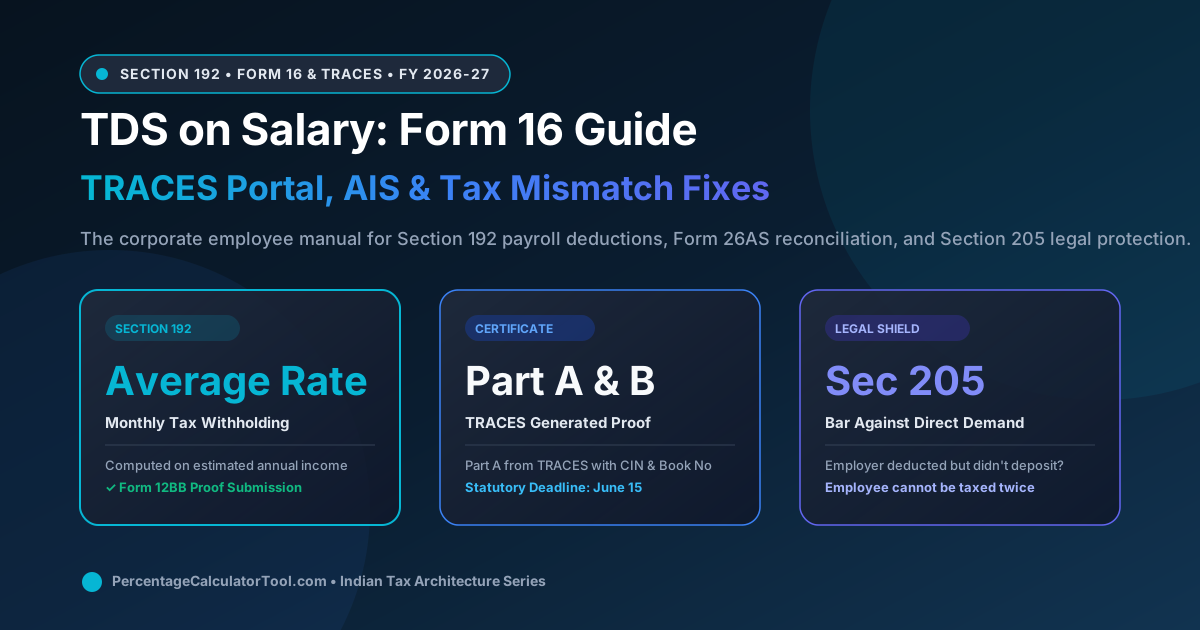
Demystifying Section 192 average withholding rate, Form 16 Part A vs Part B, Form 26AS mismatch corrections, and Section 205 legal protections.
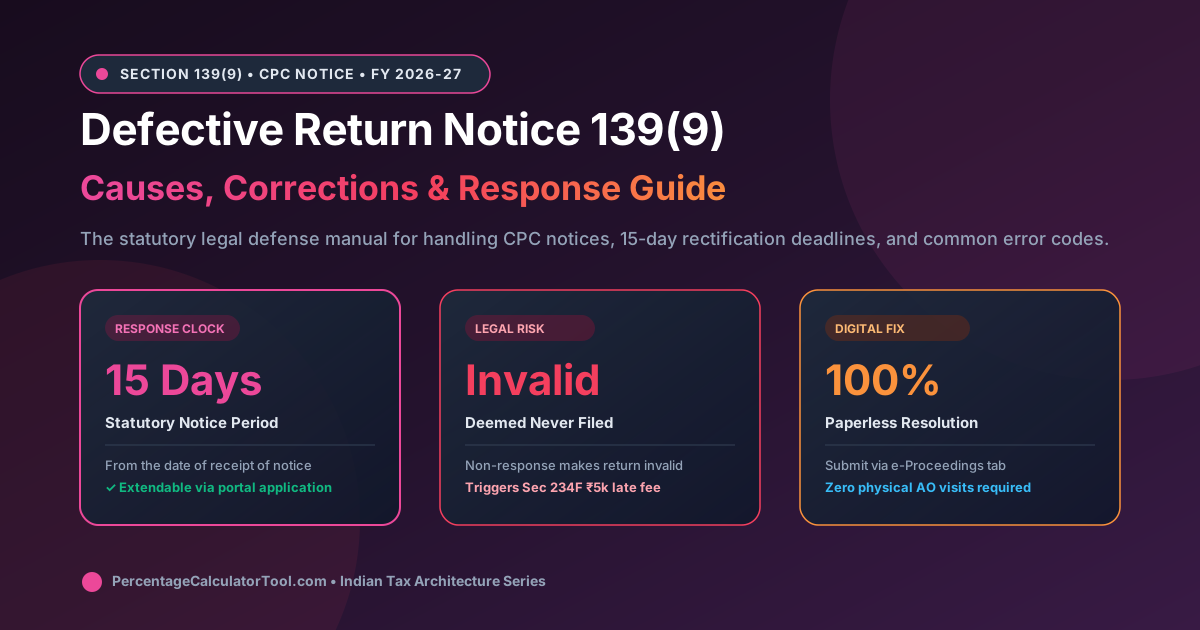
How to handle CPC defective notices. The 15-day response countdown, top 4 error code fixes, Agree vs Disagree decisions, and JSON upload steps.
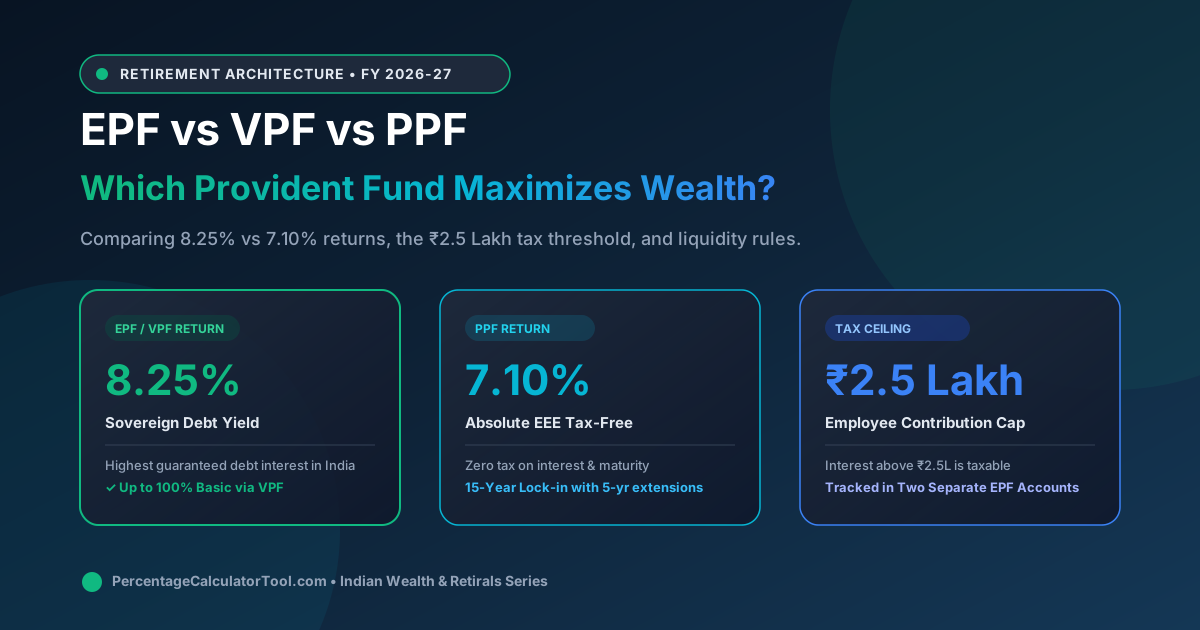
Compare 8.25% sovereign yield with 7.10% PPF. Unpack Rule 9D ₹2.5L tax limits and 20-year wealth trajectories.
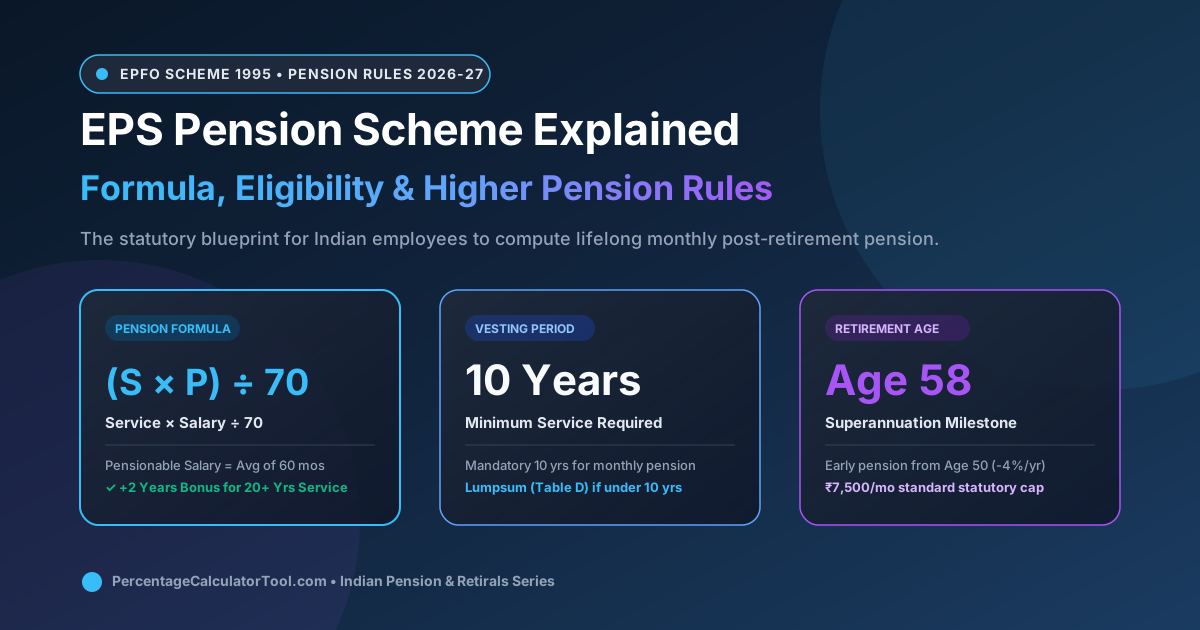
Calculate your guaranteed monthly lifelong annuity under EPS-95. 10-year vesting rules, early pension at 50, and higher pension options.
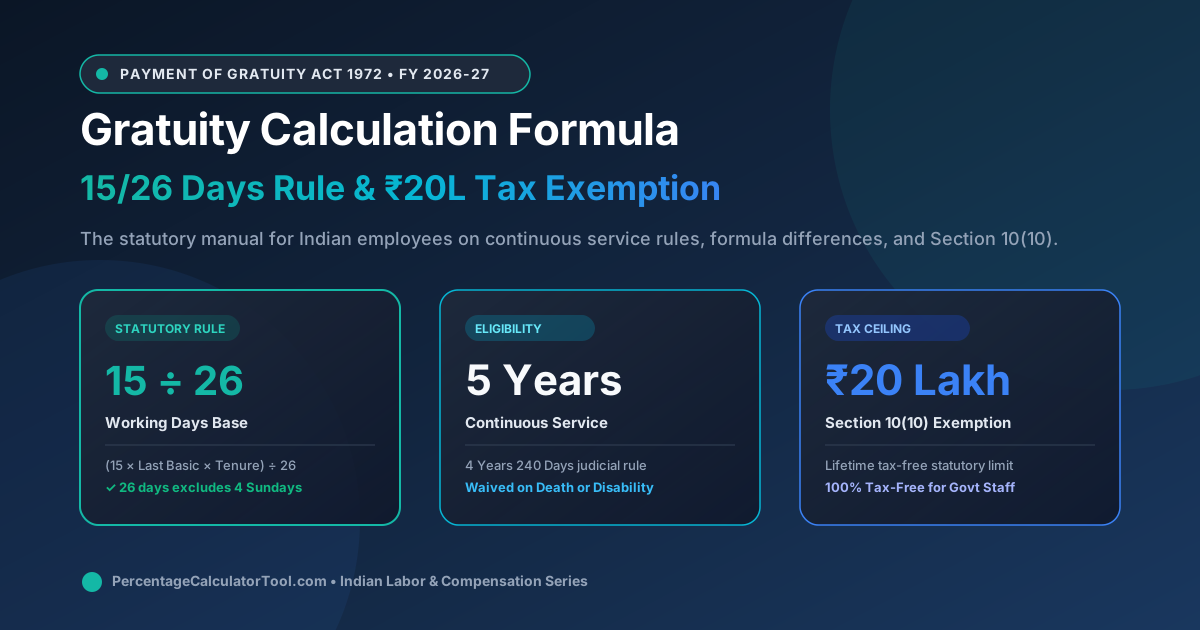
Master the 15/26 statutory formula, 4 years 240 days continuous service threshold, and ₹20 Lakh tax-free limit under Section 10(10).
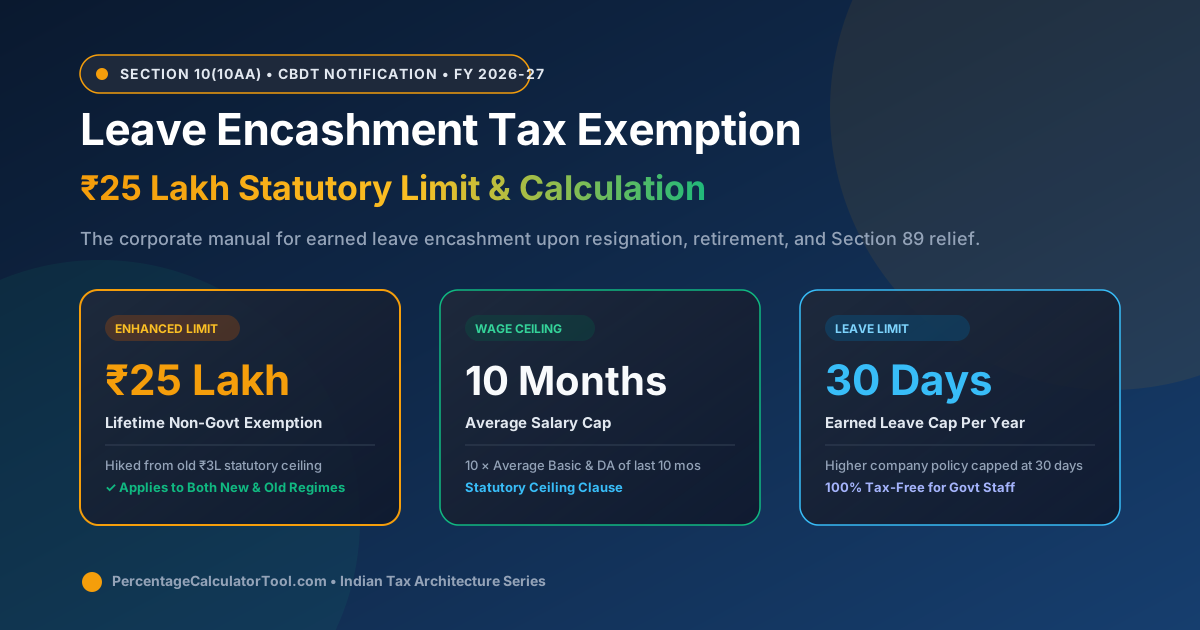
Master Section 10(10AA) 4-factor exemption test, the enhanced ₹25 Lakh statutory ceiling, 30-day annual cap, and Section 89 relief.
Complete state-by-state PT guide. Article 276(2) ₹2,500 ceiling, Karnataka & Maharashtra slabs, and zero-PT zones like Delhi NCR.
Master Section 10(13A) and Rule 2A. Explore the 3-factor least test, the 4-metro definition, ₹1 Lakh landlord PAN mandate, and Section 194-IB TDS.
Rule 3(2) statutory car valuation. Learn why ₹1,800/mo vs ₹2,400/mo slabs, ₹900 driver rules, and corporate car leasing save over ₹1.5 Lakhs annually.
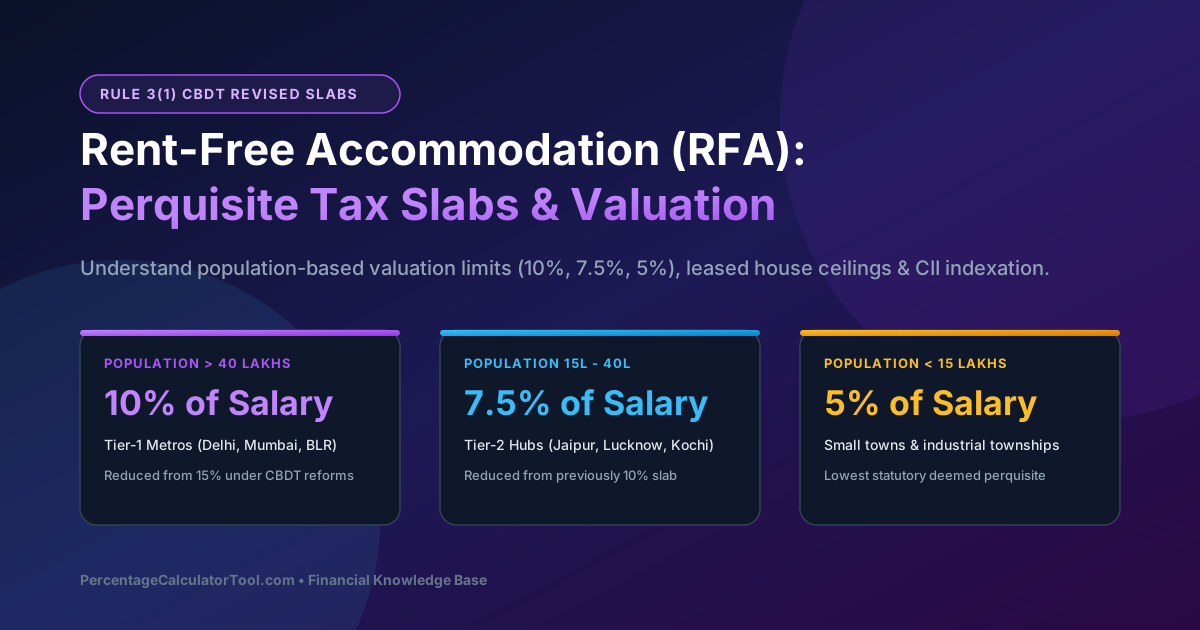
CBDT amended Rule 3(1) population slabs: 10%, 7.5%, and 5%. Discover leased accommodation caps, furniture perquisites, and the Cost Inflation Index ceiling.
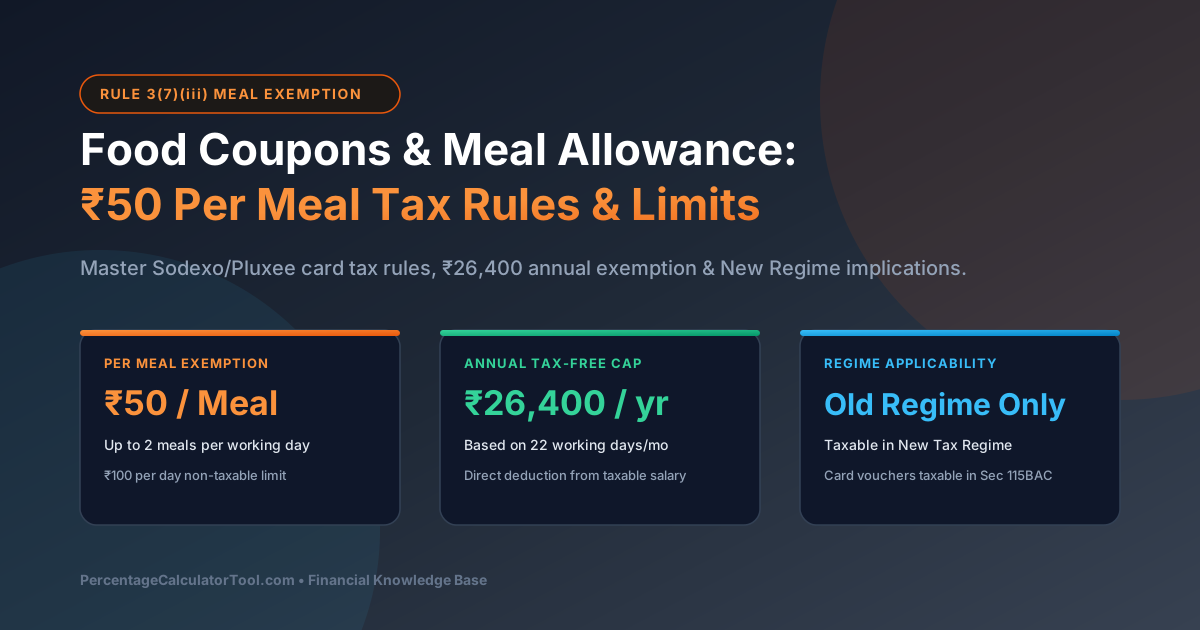
Rule 3(7)(iii) mechanics: How ₹50 per meal yields ₹26,400 tax-free on Pluxee/Sodexo cards. Why meal coupons are fully taxable in the New Tax Regime.
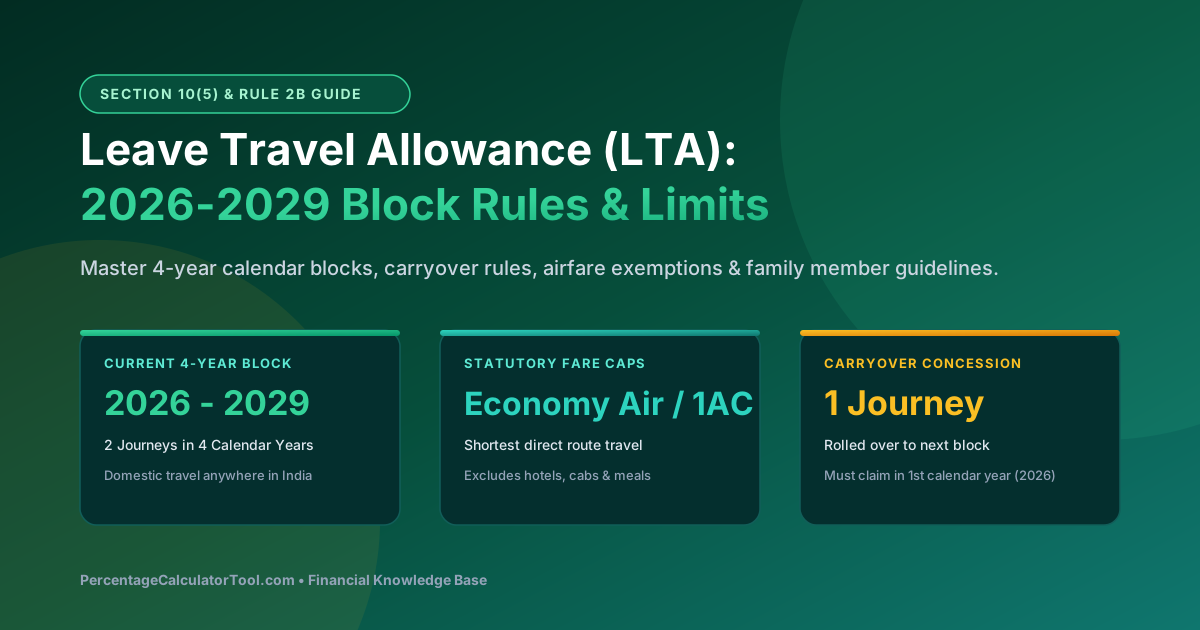
Section 10(5) and Rule 2B guide for the 2026-2029 block. Learn 2-journey limits, carryover rules, economy airfare caps, and family restrictions.
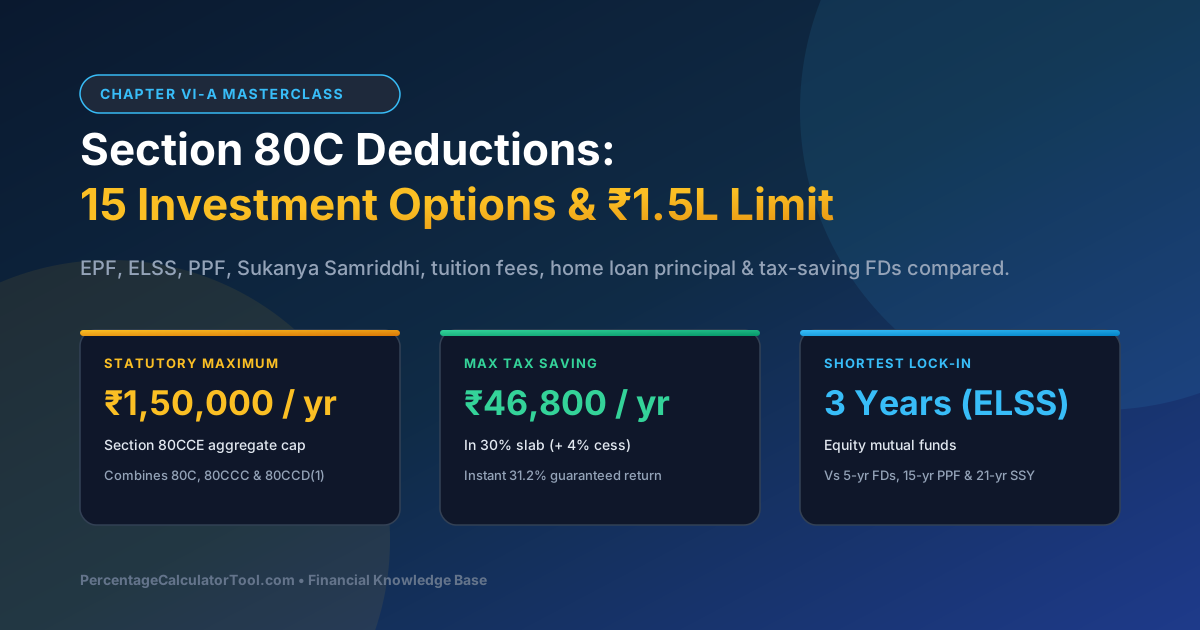
Complete masterclass on the ₹1.5L 80CCE ceiling. Compare EPF, ELSS, PPF, Sukanya Samriddhi, tuition fees, and home loan principal repayments.
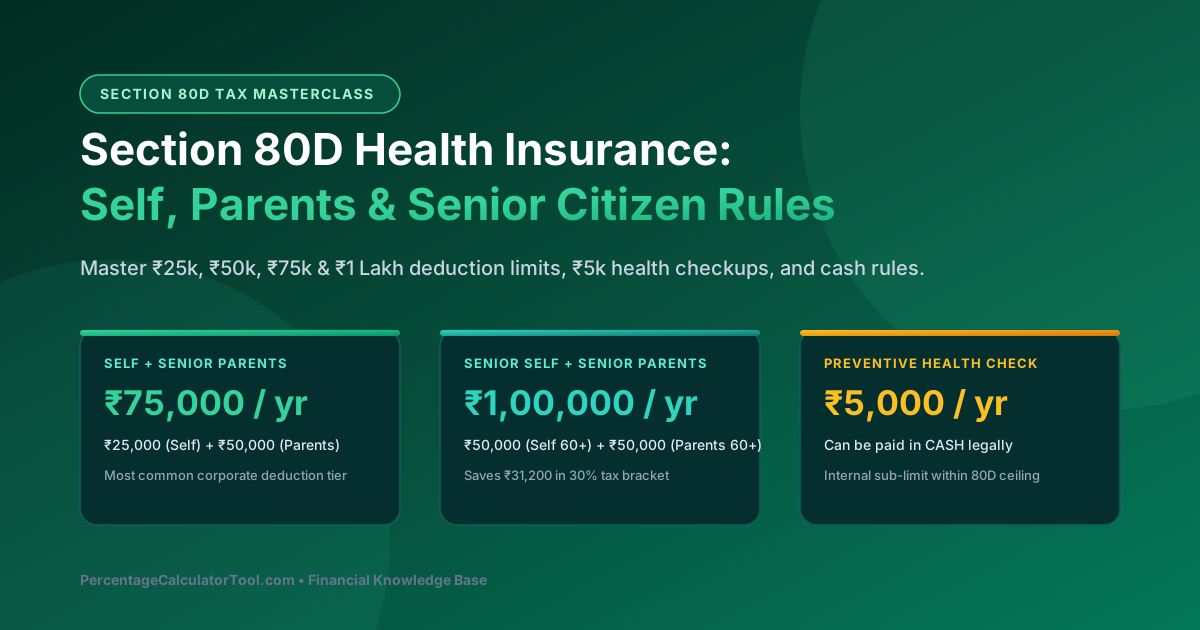
Master ₹25k, ₹50k, ₹75k, and ₹1 Lakh limits under Section 80D. Learn ₹5,000 cash health checkups and medical expense write-offs for senior parents.
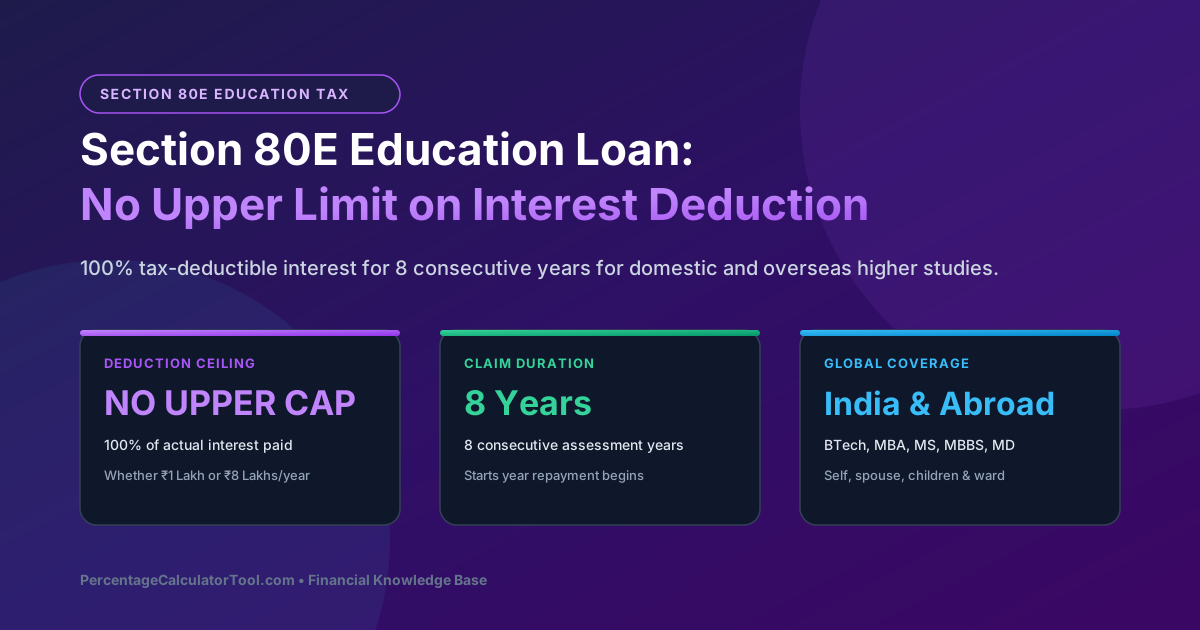
100% uncapped interest deduction for 8 consecutive years. Comprehensive rules for higher education in India and overseas master's degrees.
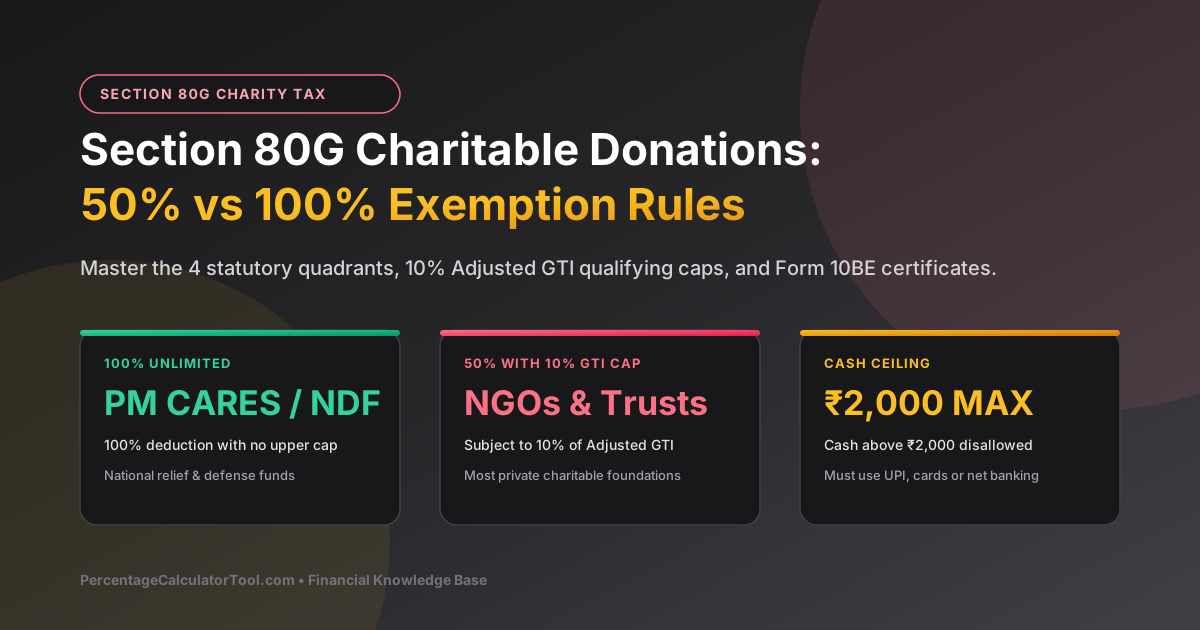
Master the 4 statutory quadrants, 10% Adjusted GTI qualifying limit, mandatory electronic Form 10BE certificates, and the ₹2,000 cash ceiling.
Compare ₹10,000 savings limits for adults vs ₹50,000 senior citizen FD deductions. Explore Section 194A bank TDS and Section 10(15)(i) post office exemptions.
Reinvestment benchmarks, net consideration formulas, the ₹10 Crore statutory cap, CGAS deposit deadlines, and 3-year lock-in clawback rules.
Save up to ₹50 Lakh on land or building sale without buying property. 5-year lock-in, approved REC/PFC/NHAI/IRFC bonds, and 5.25% taxable yields.
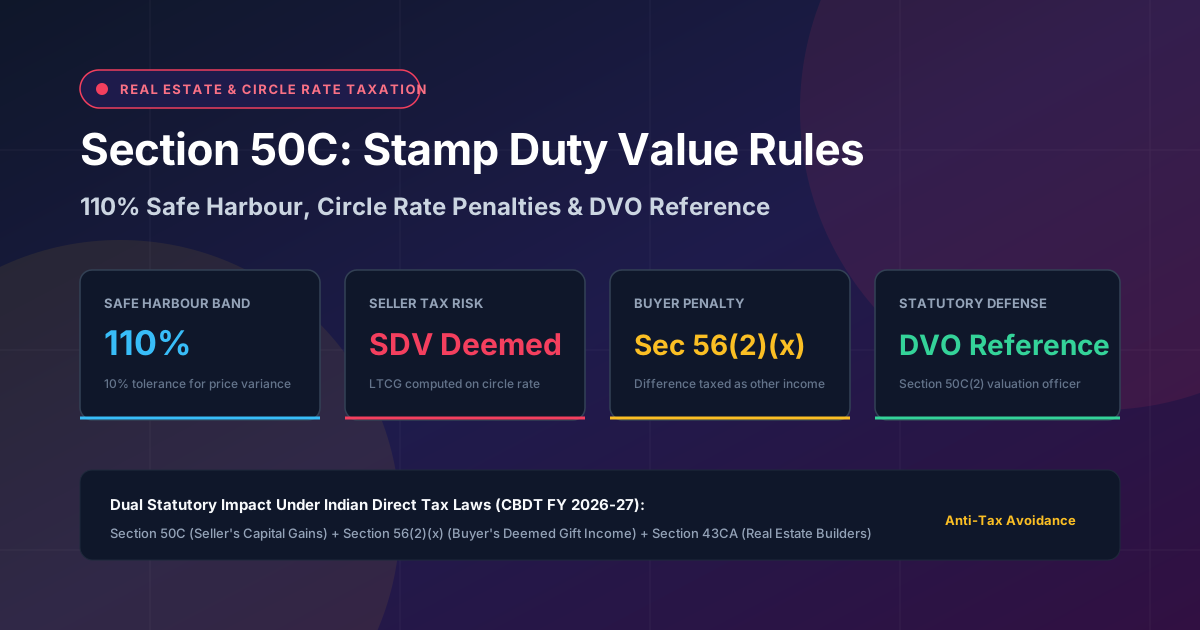
110% safe harbour band, agreement date proviso, Section 56(2)(x) buyer deemed gift penalties, and Section 50C(2) DVO valuation objections.
Account A vs B comparison, Section 139(1) deposit deadlines, Form A to G, 60-day withdrawal expenditure rules, and unspent tax treatment at Year 3.
1% TDS on ₹50L+ deals, higher of price or circle rate rule, parking/club charges inclusion, Form 26QB filing, Form 16B, and penalty risks.
Determine residential status under Section 6: 182-day rule, 60+365 days, 120-day rule for ₹15L+ Indian income, Section 6(1A) deemed residency, and RNOR tax shields.
Tax-free NRE interest under Sec 10(4)(ii), 30% TDS on NRO interest under Sec 195, FCNR(B) currency deposit shields, and $1M repatriation via Form 15CA/15CB.
Avoid 20%+ TDS on gross property sales. Complete guide to Section 197 Lower TDS Certificate via Form 13 on TRACES, buyer TAN requirements, and Form 27Q filing.
Eliminate double taxation under Section 90/90A. Mandatory electronic Form 10F on e-filing portal, TRC verification, and reducing NRO interest TDS from 30% to 10%–15%.
Mandatory reporting for ROR taxpayers holding foreign bank accounts, US stocks/RSUs (Table A1-G), SBI TT buying conversion, ₹10L Black Money Act penalty, and Budget 2024 ₹20L relief.
Post-Budget 2024 rules: 12.5% LTCG beyond ₹1.25L exemption, 20% STCG, Section 50AA pure debt slab rates, 24-month hybrid rules, and SIP FIFO mechanics.
Section 70 inter-source set-off rules, Section 71 inter-head bans, 8-year carry forward under Section 74, wash sale freedom, and annual ₹1.25L LTCG gain harvesting.
Section 43(5)(d) non-speculative business status, ICAI absolute turnover calculation, Section 44AB ₹10 Crore audit limits, STT deductibility, and ITR-3 compliance.
Section 43(5) non-delivery equity definition, Section 73 strict loss set-off walled garden, 4-year carry forward lifespan, why Section 44AD is barred, and ITR-3 filing.
Classical dividend taxation under Income from Other Sources, 10% TDS above ₹5,000 under Sec 194/194K, Form 15G/H submission, Section 57(i) 20% interest cap, and advance tax relief.
Demystify the two-stage tax event: Stage 1 perquisite on exercise FMV and Stage 2 capital gains on sale. Startup deferral u/s 192(1C), unlisted shares, and double-tax avoidance.
Compare real equity sweat shares (Section 54 Companies Act, 3-year lock-in) with synthetic phantom stocks & cash SARs. Corporate tax deductibility and ITR reporting.
Complete guide to surcharge rates (10%, 15%, 25%, 37%) across New vs. Old Tax Regimes. Marginal relief step-by-step formula for ₹50L, ₹1Cr, and ₹2Cr cliff edges.
The ₹50,000 annual aggregate threshold trap, exhaustive relative definition, tax-free wedding gifts, real estate safe harbor tolerance bands, and mandatory gift deeds.
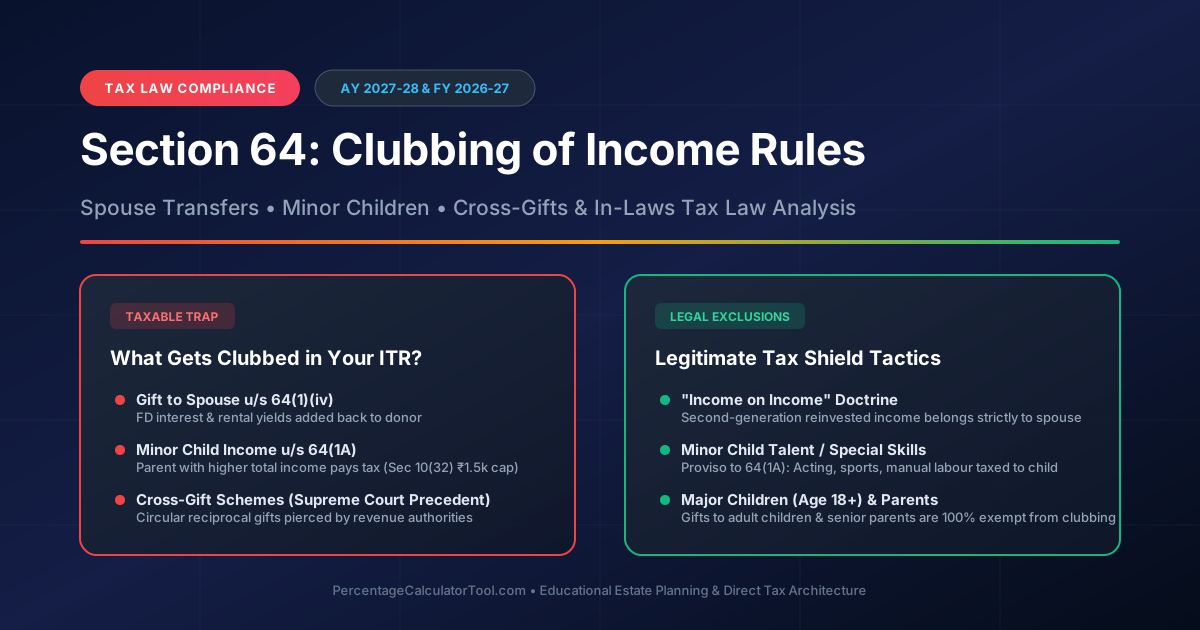
Anti-avoidance rules for spouse asset transfers, minor child earnings & ₹1,500 cap, cross-gifting Supreme Court precedent, and the landmark income-on-income doctrine.
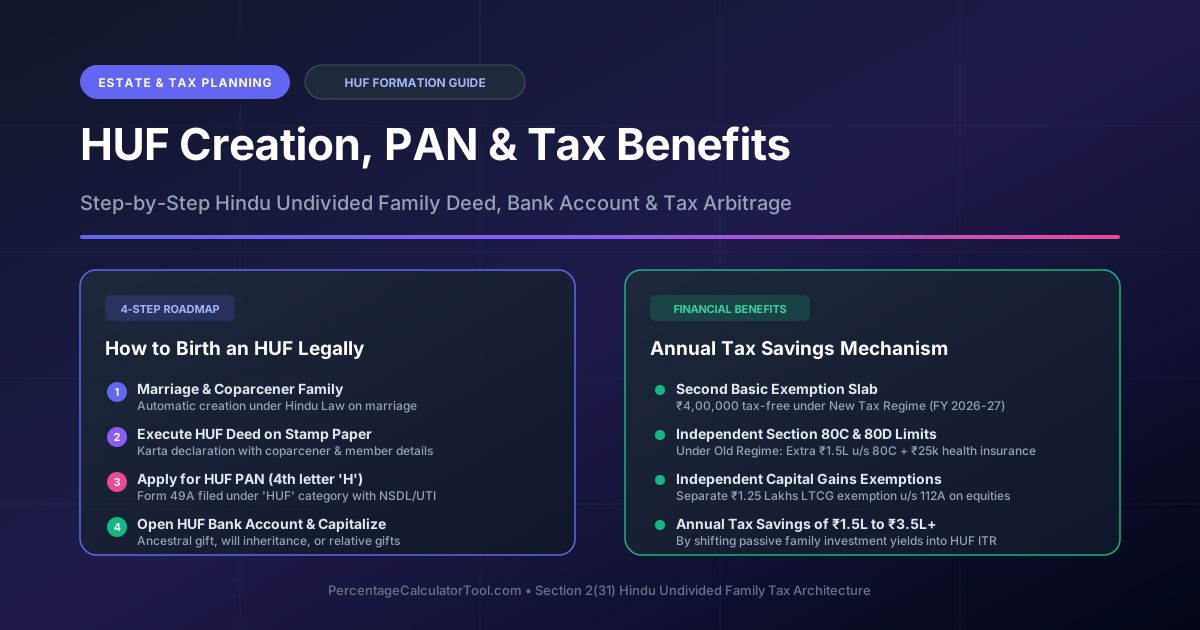
Step-by-step formation of a Hindu Undivided Family. Drafting the deed, applying for HUF PAN (4th letter 'H'), opening bank/Demat accounts, and saving ₹1.5L+ annually.
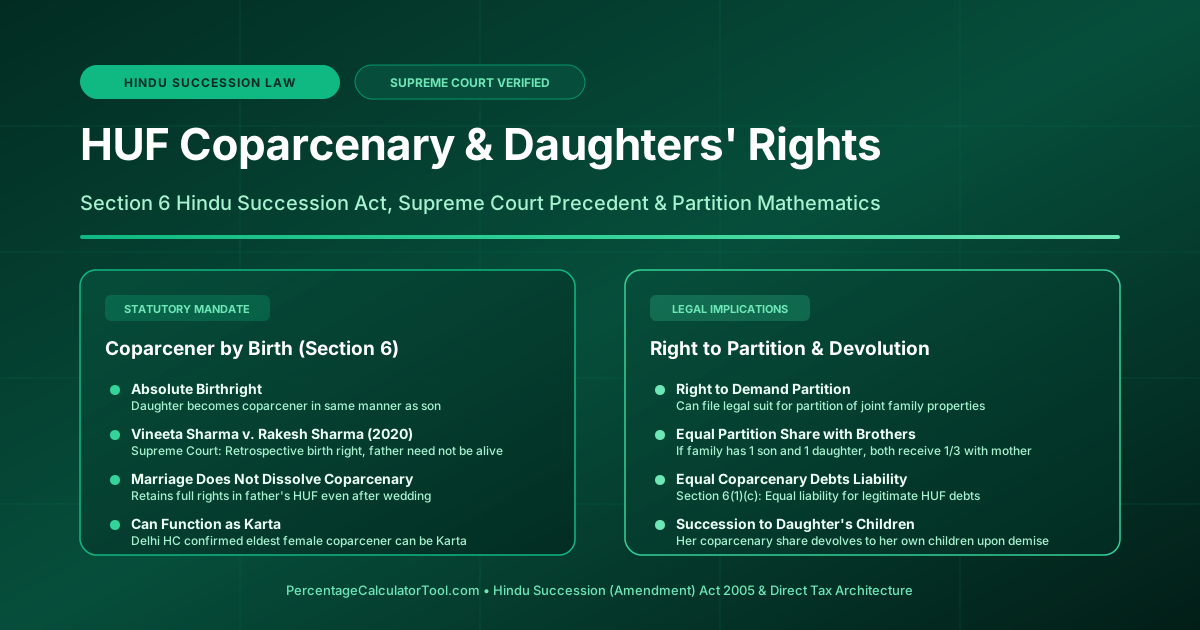
Section 6 Hindu Succession Act analysis, Supreme Court Vineeta Sharma (2020) ruling, coparcenary by birth, female Karta rights, and equal partition mathematics.
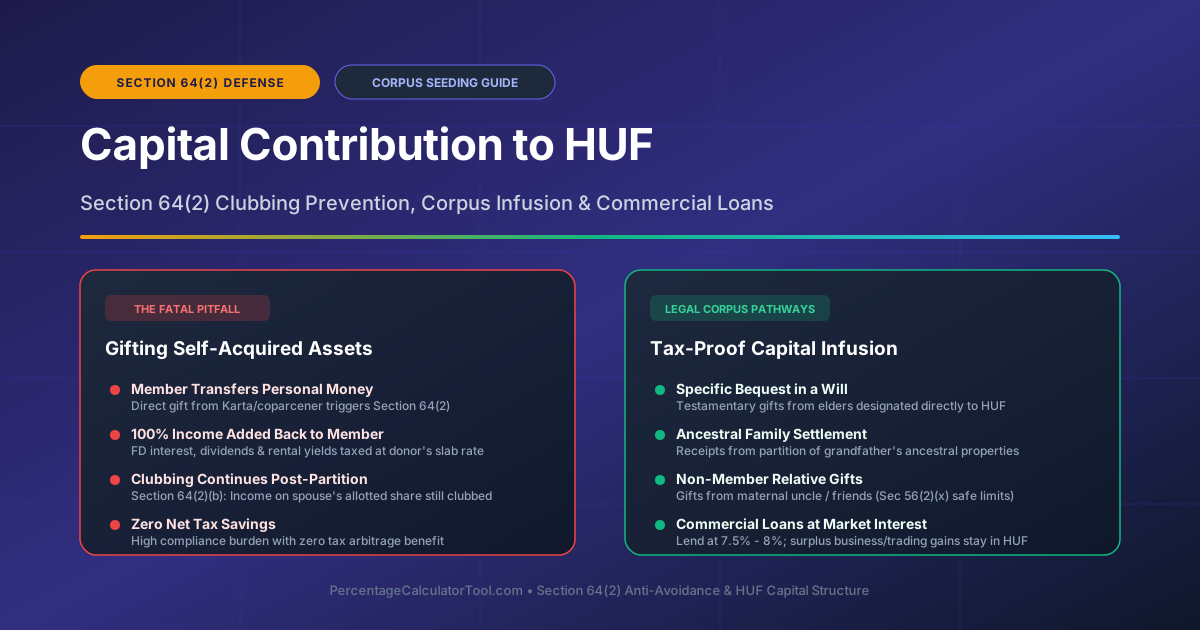
Avoid the fatal Section 64(2) trap. Compliant corpus building via Will bequests, ancestral family settlements, commercial loans at 7.5%, and non-member relative gifts.
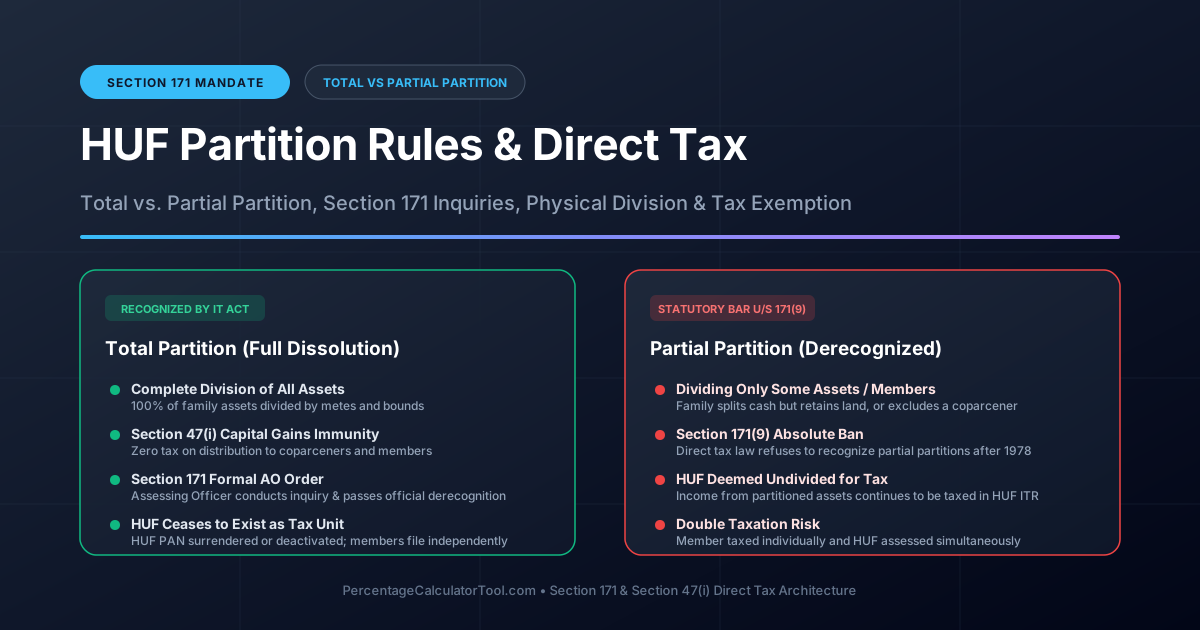
Section 171 assessment orders, why partial partitions are derecognized u/s 171(9), the metes & bounds physical division test, and Section 47(i) capital gains immunity.
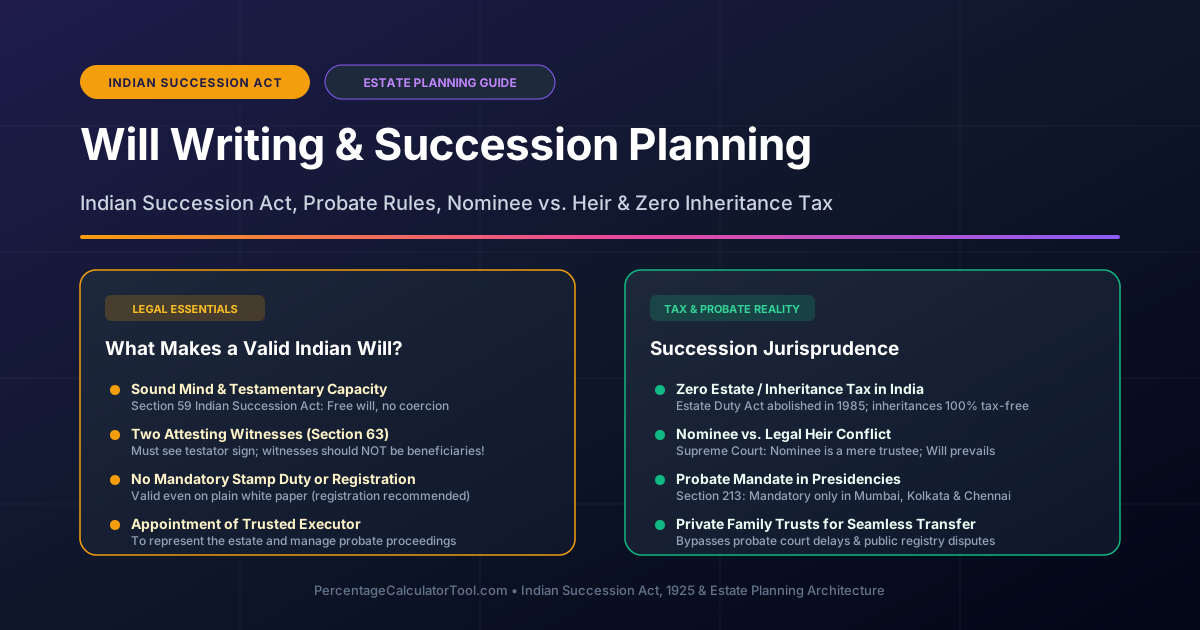
Indian Succession Act compliance, 2 independent witnesses, executor appointment, probate rules in Mumbai/Kolkata/Chennai, nominee vs. heir battles, and zero estate tax.
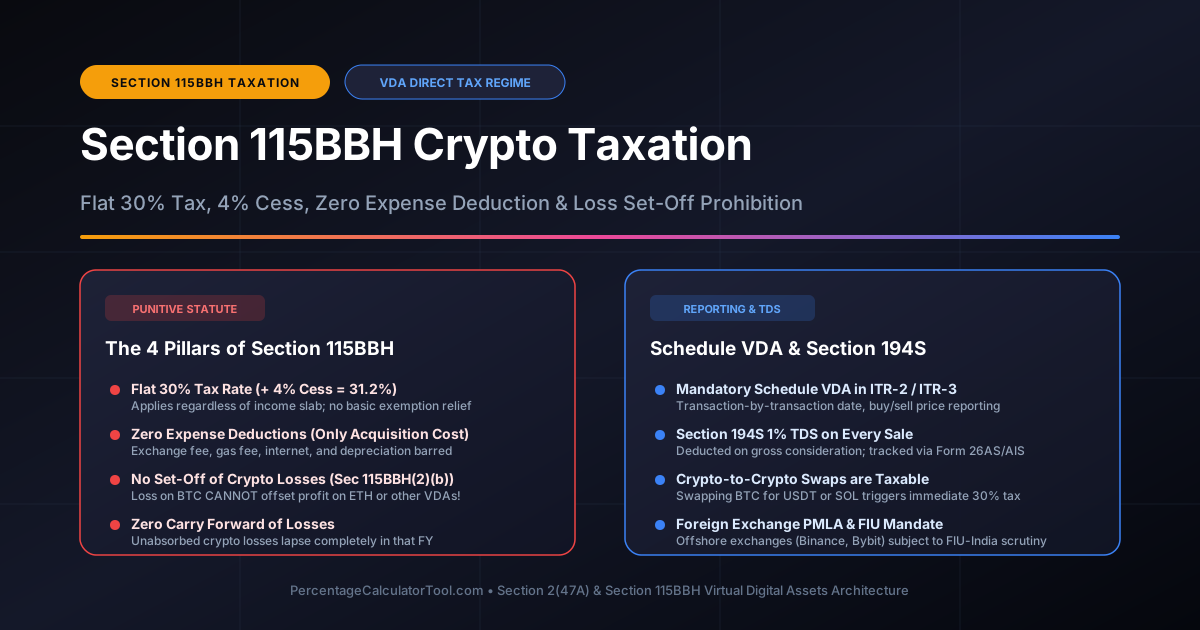
Statutory 30% flat tax, zero expense deductions (only buy cost), strict ban on offsetting crypto losses, token-to-token swap taxes, and Schedule VDA ITR reporting.
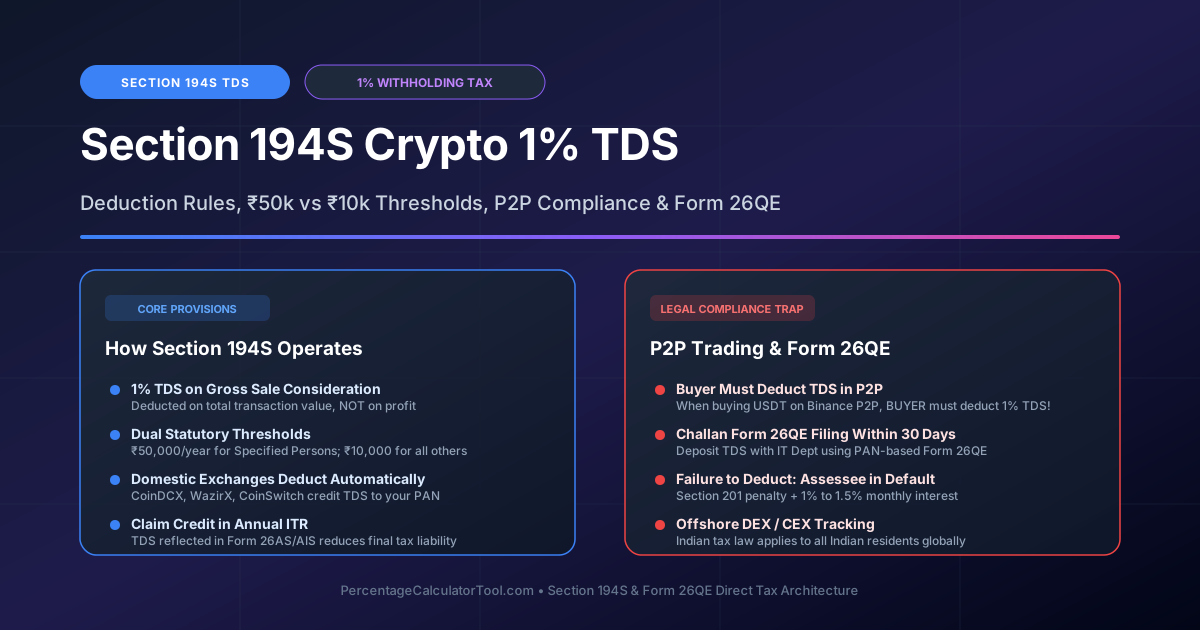
1% TDS withholding rules, ₹50,000 specified person vs ₹10,000 threshold, buyer obligation in P2P trades on Binance, Challan Form 26QE, and Form 16D issuance.
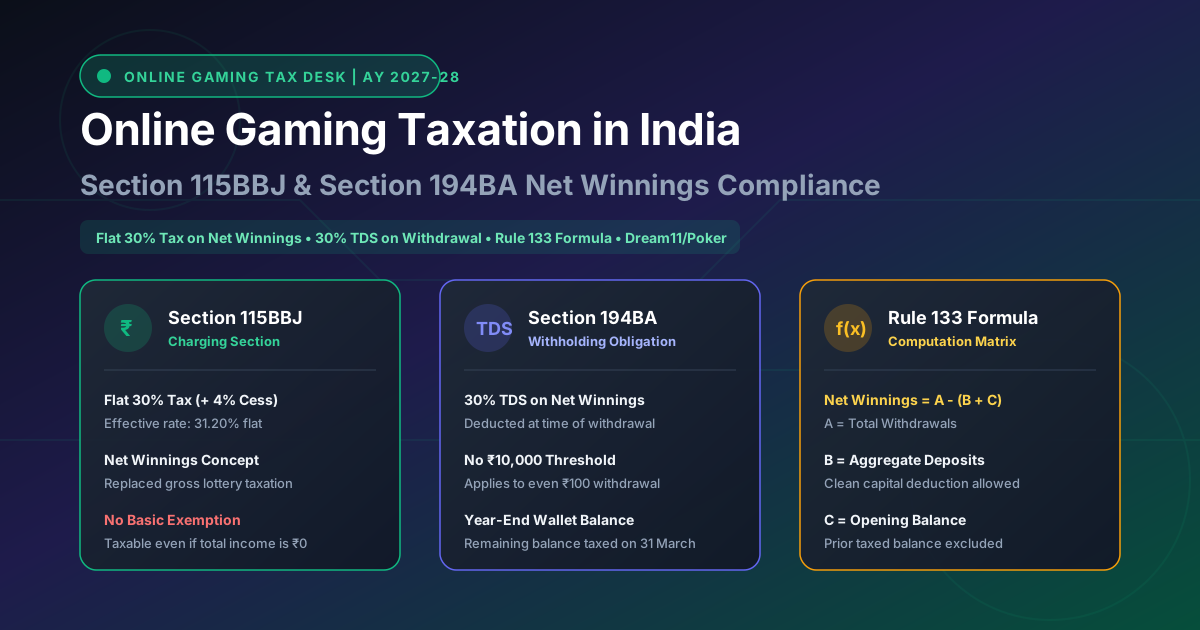
Flat 30% tax on net winnings, Rule 133 formula A - (B + C), 30% TDS on withdrawals without minimum threshold, Dream11/poker rules, and year-end wallet balance tax.
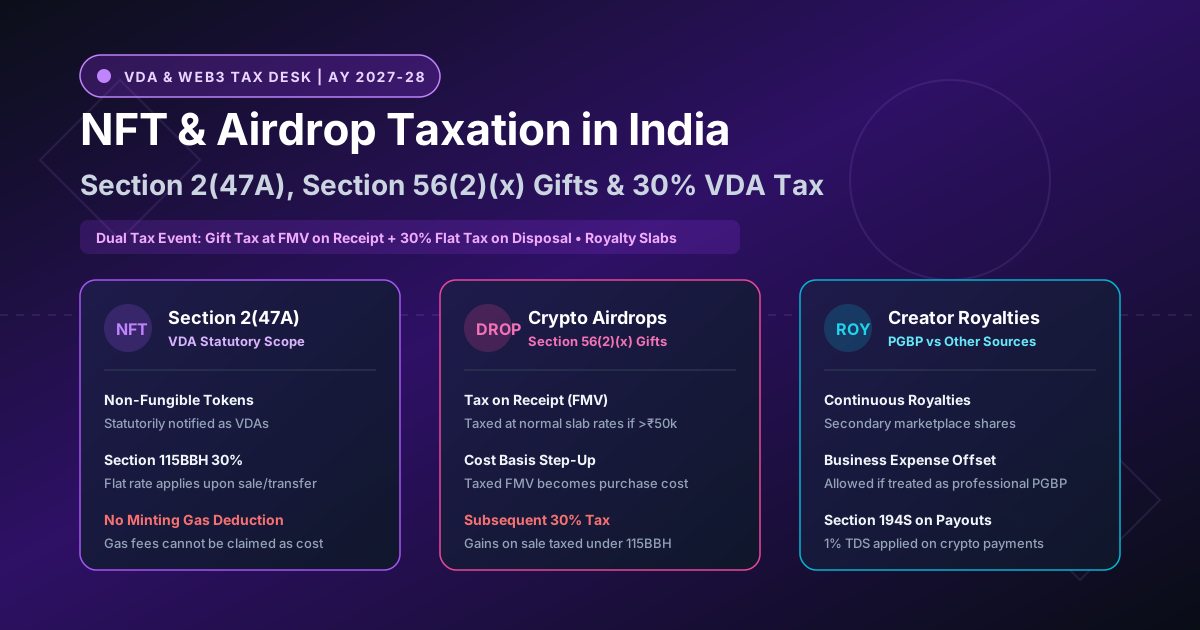
Dual tax event on crypto airdrops, Section 49(4) stepped-up FMV cost basis, flat 30% capital gains, disallowed minting gas fees, and creator royalties.
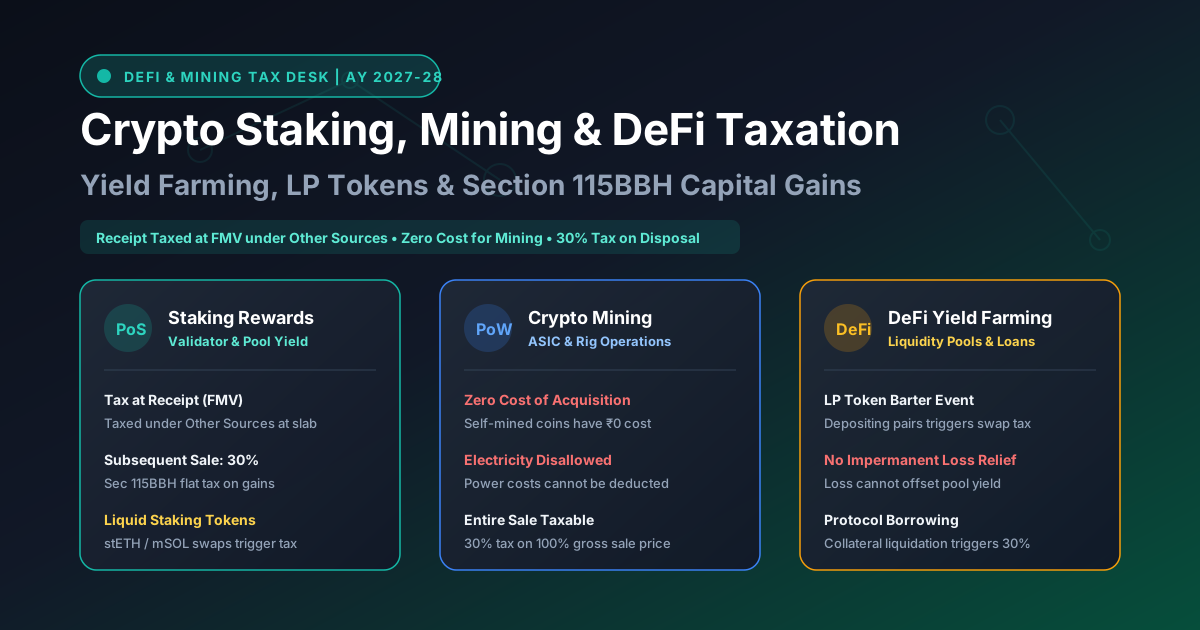
PoS validator yields taxed under Other Sources, zero cost basis and disallowed electricity for mining, LP token swaps, and impermanent loss rules.
Complete guide to 6% digital vs 8% cash deemed profits, ₹3 Cr digital turnover limits, 5-year lock-in debarment, and audit exemption under Section 44AD.
Flat 50% deemed profit calculation, ₹75 Lakh enhanced receipts cap, zero book maintenance, no 5-year lock-in restriction, and advance tax rules.
10-vehicle fleet limit, ₹1,000/ton per month for heavy goods vehicles, ₹7,500/month for light vehicles, partner remuneration deductions, and ITR-4 filing.
₹1 Cr vs ₹10 Cr twin 5% cash test, F&O turnover computation, Form 3CA vs 3CB reports, Form 3CD reporting clauses, and Section 271B penalty defense.
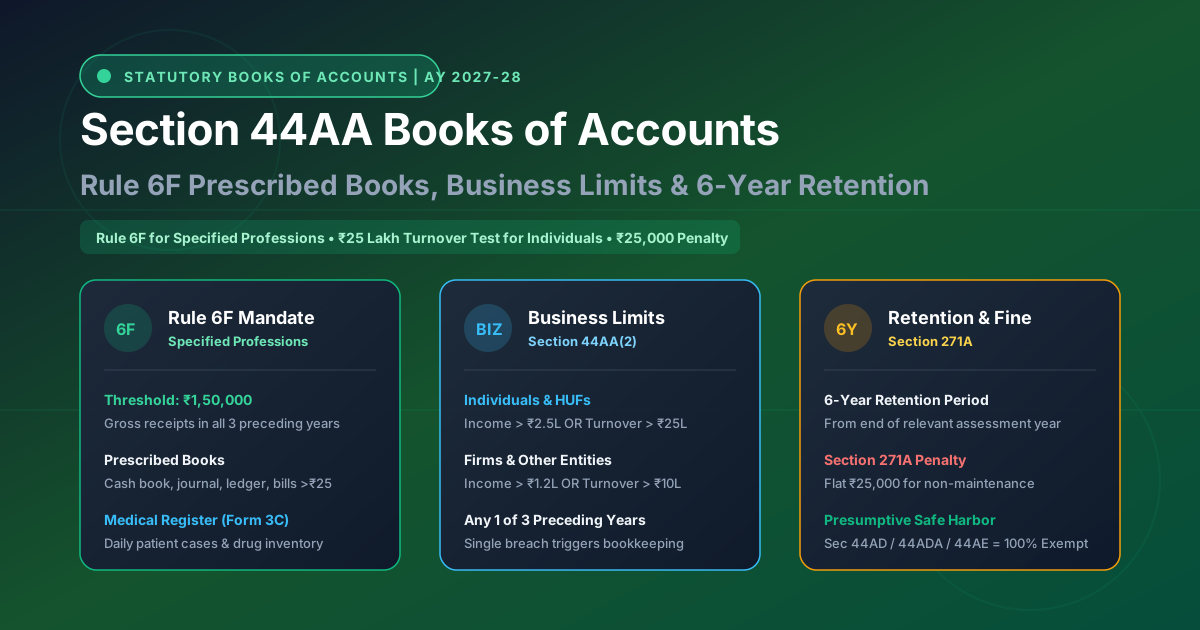
Specified professions ₹1.5L test, business ₹25L turnover / ₹2.5L income thresholds, mandatory Rule 6F journals and ledgers, 6-year retention, and Section 271A penalties.
Concessional rates on foreign exchange assets, denial of Chapter VI-A deductions, Section 115F reinvestment rollovers, and Section 115G ITR filing immunity.
The 1-3 year tax holiday on overseas income, Section 10(15) FCNR/RFC interest exemption, US 401(k) structuring, and Schedule FA filing immunity.
Intent-based FEMA rules vs physical day-count tax tests, mandatory NRO account redesignation, Section 10(4) NRE interest rules, and RBI compounding procedures.
Section 49(1) ancestral cost basis, 12.5% LTCG rates, Section 197 Lower TDS Certificate (Form 13), Form 15CB CA certification, and AD Bank wire protocols.
120% tax and penalty, flat ₹10 Lakh Section 43 penalty for Schedule FA omission, tech employee RSUs/ESPP rules, and the ₹5 Lakh bank safe harbor proviso.
₹10,000 threshold, quarterly installments (15%-45%-75%-100%), safe harbor cushions (12% and 36%), capital gains estimation, and senior citizen exemptions.
1% monthly interest formulas, 90% advance tax threshold, quarterly deferment computations, and Rule 119A rounding rules for AY 2027-28.
Statutory appropriation sequence (Fee -> Interest -> Tax), Minor Head 300 challan generation, assessee in default risks, and Section 221 penalties.
0.5% monthly refund interest, 10% threshold filter, Other Sources taxability, Section 245 demand adjustments, and Section 154 rectification workflows.
₹5,000 / ₹1,000 late fees, 31st Dec cut-off, Section 80 loss lapsing, New Tax Regime default locks, and Section 139(8A) ITR-U remedies for AY 2027-28.
3-month limitation deadlines, CASS algorithmic risk triggers, 30-day prima facie adjustment responses, and faceless e-Proceedings compliance.
NaFAC multi-unit grid (AU, VU, TU, RU), mandatory Show Cause Notice requirements, Section 144B(6)(vii) video hearing rights, and appellate remedies.
Mandatory Section 148A preliminary inquiries, 3-year vs extended limitation under Section 149, ₹50 Lakh asset criteria, and Section 151 sanctions.
Civil Court discovery powers, statements on oath, 15-day book impounding limits, retraction of coerced statements, and cross-examination rights.
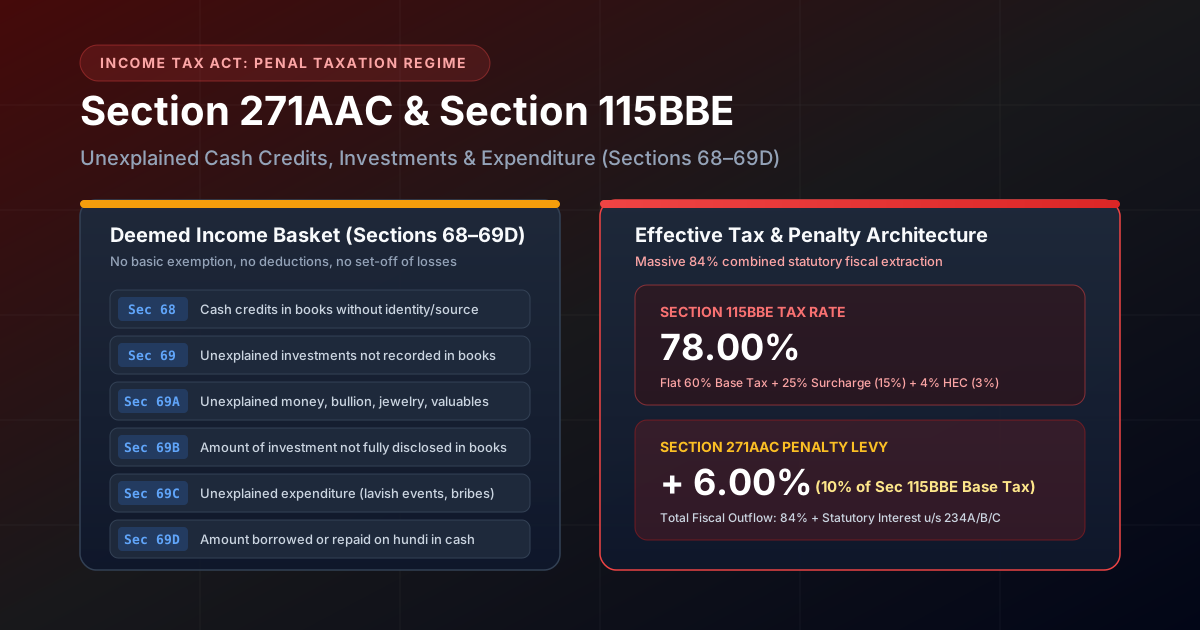
The 4 default triggers, mandatory SCN proviso, Supreme Court Velukutty fair estimate doctrine, 78% Section 115BBE tax risks, and Rule 46A fresh evidence.
50% under-reporting vs 200% misreporting penalties, the six statutory sins under Section 270A(9), safe harbors u/s 270A(6), and Form 68 immunity.
Deemed income basket under Sections 68–69D, 3-fold evidentiary test, loss set-off bans, 10% penalty mechanics, and survey stock judicial defenses.
Rigorous imprisonment up to 7 years, Section 278E presumption of mens rea, CJM trial procedures, bail rules, and K.C. Builders quashing precedents.
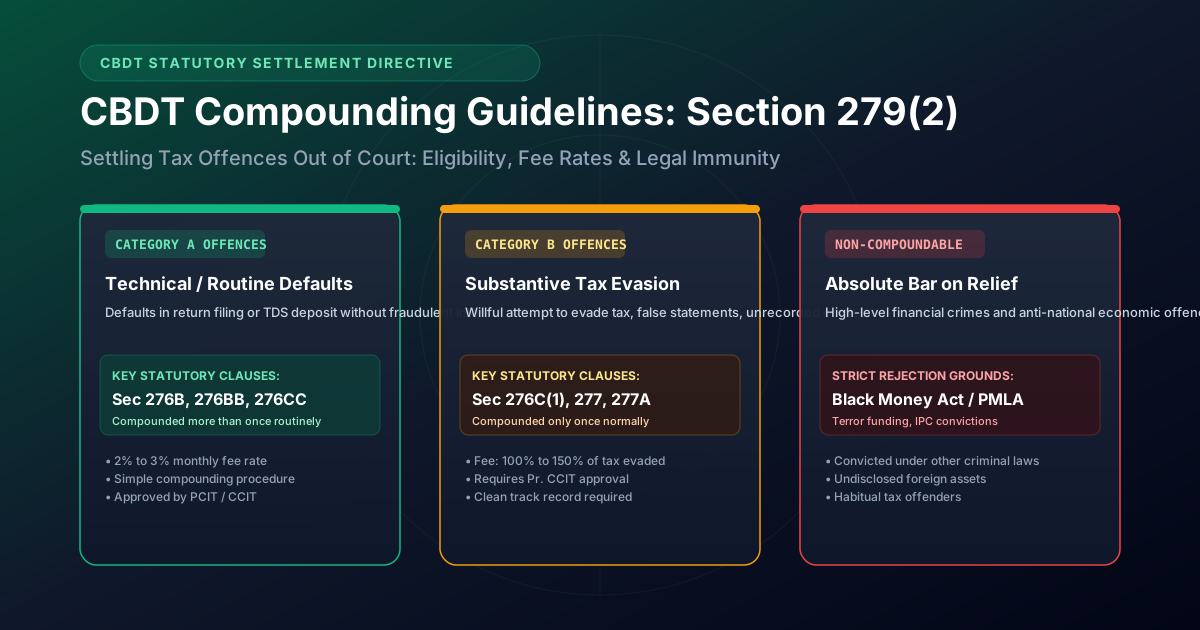
Category A vs B offences, mathematical fee computation formulas, prosecution establishment charges, delay condonations, and trial acquittals u/s 320 CrPC.
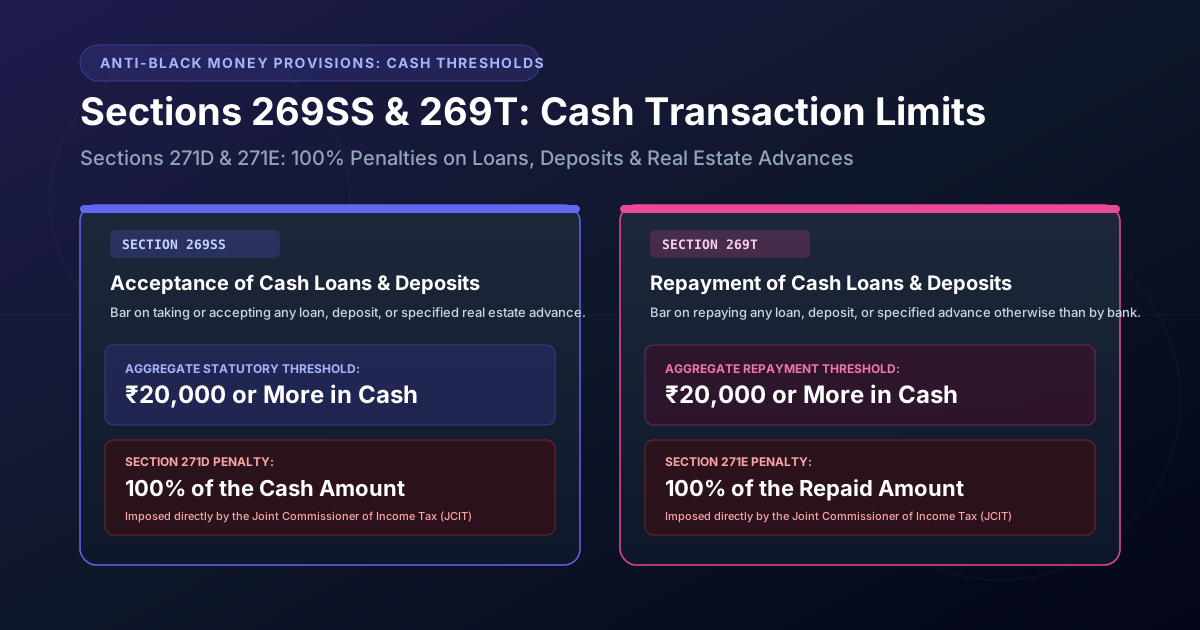
The ₹20,000 threshold aggregation rules, 100% penalties u/s 271D & 271E, immovable property advances, journal entries, and Section 273B defenses.
Compare Section 115BAA 22% rate (25.17% effective), 115BAB manufacturing benefits, Section 115JB MAT exemption, lost deductions, Section 80JJAA and 80M advantages.
15% MAT computation on Schedule III book profits, positive/negative additions, loss/depreciation adjustments, 15-year Section 115JAA MAT credit carry-forward, and 115BAA transition.
100% tax holiday for 3 out of 10 years u/s 80-IAC, ₹100 Cr turnover cap, DPIIT recognition, IMB certification, angel tax abolition, Form 10CCB audit, and Section 192(1C) ESOP relief.
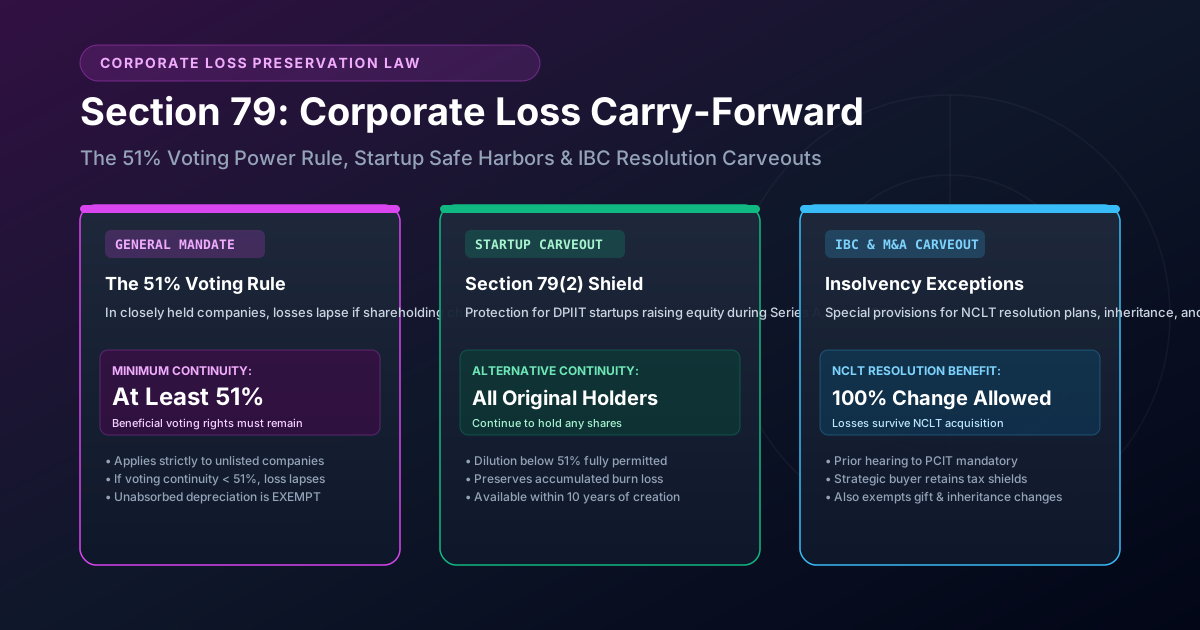
51% shareholding continuity mandate, unabsorbed depreciation survival doctrine, Section 79(2)(a) startup carveout, Section 79(2)(c) NCLT IBC exemption, and M&A tax structuring.
Shift from company-level buyback distribution tax to deemed dividend u/s 2(22)(f), Section 46A capital loss creation, 10% TDS u/s 194, Section 80M corporate deduction, and tax modeling.
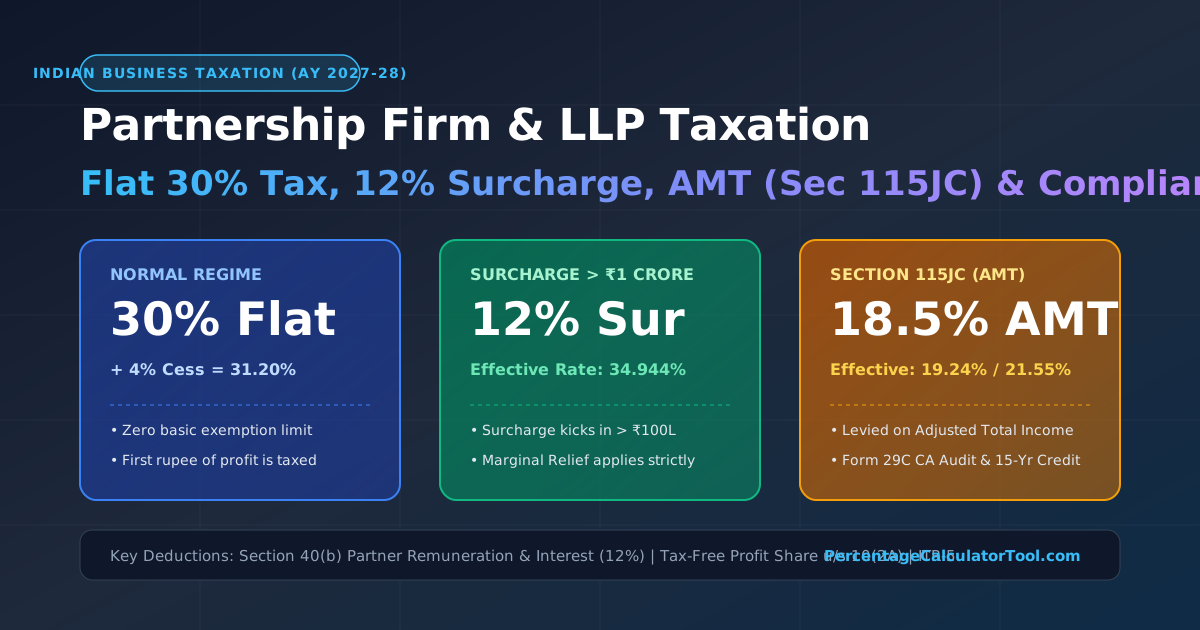
Master flat 30% tax rate, 12% surcharge over ₹1 Crore, Section 115JC Alternate Minimum Tax (18.5%), Form 29C CA report, 15-year AMT credit carry forward, and Firm vs LLP vs Company.
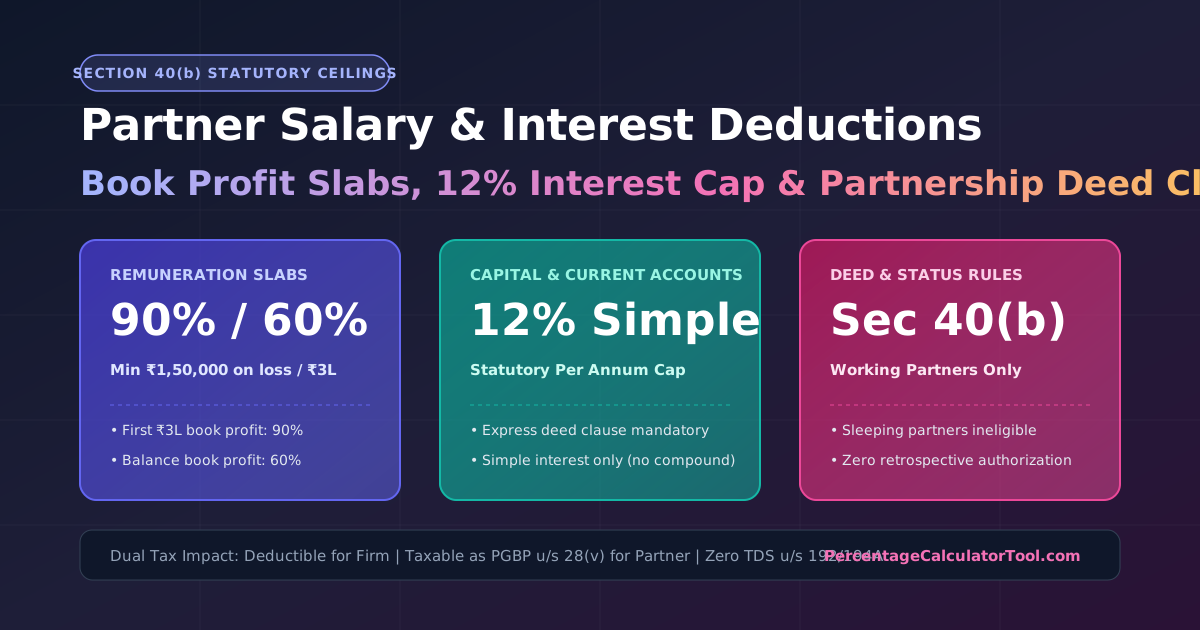
Deduct partner remuneration via 90%/60% book profit formulas, 12% simple interest cap, working partner rules, deed drafting clauses, zero TDS, and tax arbitrage from 31.2% to 0%.
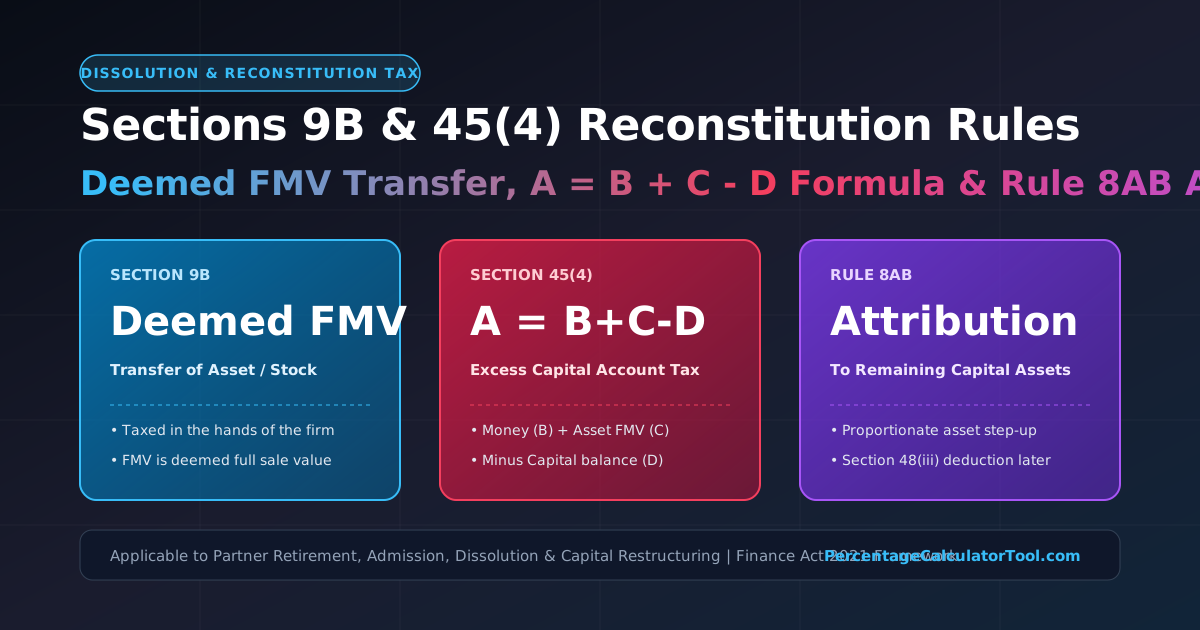
Deemed FMV transfer u/s 9B, Section 45(4) excess capital formula A = B + C - D, revaluation stripping, Rule 8AB asset attribution, Section 48(iii) deductions, and retirement planning.
Complete guide to 0% capital gains conversion: ₹60L turnover cap, ₹5Cr asset limit, 50% 5-year continuity, Section 47A(4) clawbacks, Section 72A(6A) loss absorption, and MAT credit trap.
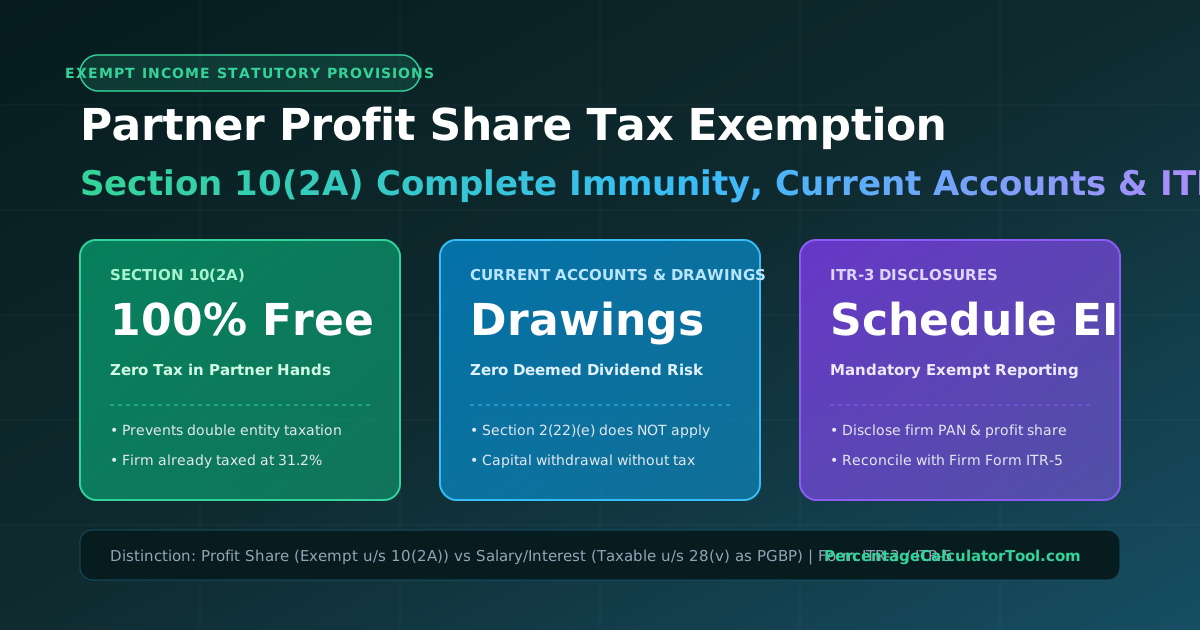
100% tax exemption under Section 10(2A), 3-bucket inflow breakdown, capital vs current accounts, non-taxable drawings, Section 56(2)(x) immunity, and Schedule EI reporting in Form ITR-3.
We use essential cookies and anonymous analytics to enhance your experience. See our Privacy Policy.