The High-Earner Inflection: 18 LPA in India's Knowledge Economy
An annual Cost to Company (CTC) of ₹18,00,000 (18 LPA) places a salaried professional inside the top 1.5% of individual income earners in India. Typically achieved by principal software architects, senior engineering managers with 7 to 12 years of experience, specialized management consultants, cloud infrastructure directors, and commercial heads, 18 LPA represents serious financial velocity.
When an employment contract states an annual CTC of ₹18,00,000, candidates naturally execute simple division:
₹18,00,000 ÷ 12 months = ₹1,50,000.00 per month
However, when your monthly salary credit notification arrives, the credited sum is between ₹1,17,500 and ₹1,26,297. A difference of roughly ₹23,700 to ₹32,500 per month is deducted. At 18 LPA, your income crosses a critical fiscal threshold: your taxable earnings surpass ₹15,00,000, which activates the highest marginal income tax slab of 30% under Indian tax law.
The CTC Disconnect: Why ₹1,50,000 Never Reaches Your Bank
Under Indian payroll conventions, Cost to Company (CTC) is an employer-centric metric. It reflects the entire financial outlay required to retain you on the corporate payroll for twelve months. It is not an agreement to transfer ₹1,50,000 into your savings account.
The difference between your gross CTC and net bank credit stems from three statutory deduction layers:
- Employer-Side Retiral Provisions: Statutory contributions paid by the organization into mandatory retiral trusts (Employer EPF contribution) and accounting reserves held for statutory severance (Gratuity). These are included inside the quoted CTC package but do not appear as earnings on your payslip.
- Employee-Side Statutory Withholdings: Compulsory deductions carved directly out of your gross salary on the paystub, including your personal Employee EPF share and State Professional Tax.
- Income Tax (TDS): Compulsory central government income tax withholdings carved directly out of your monthly earnings based on your applicable tax regime slab rates, including the 30% top bracket.
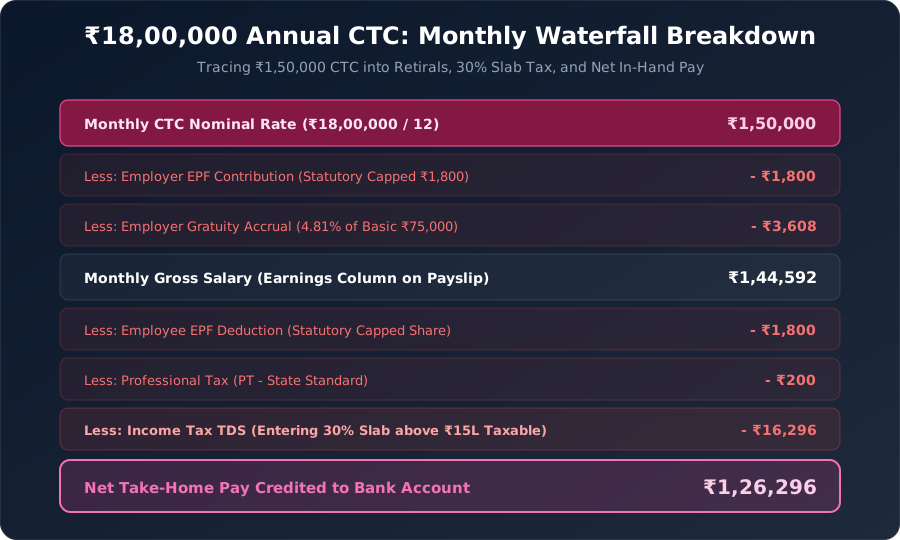 Figure 1: Visual waterfall tracing how a ₹1,50,000 monthly CTC is distributed into statutory retirals, 30% slab tax, and ₹1,26,297 net take-home pay.
Itemized Paystub Breakdown: From ₹1,50,000 to ₹1,26,297
Let us inspect the exact mathematics of a typical 18 LPA corporate pay structure under the standard 50% Basic Salary structure with capped Employee Provident Fund (EPF):
| Salary Component | Calculation Rule | Annual (INR) | Monthly (INR) | Classification |
|---|---|---|---|---|
| Basic Salary | 50% of CTC | ₹9,00,000 | ₹75,000 | Taxable Base Earnings |
| House Rent Allowance (HRA) | 40% of Basic (Non-Metro) | ₹3,60,000 | ₹30,000 | Taxable / Exempt u/s 10(13A) |
| Special Allowance | Balancing Residual Component | ₹4,75,110 | ₹39,593 | Fully Taxable Allowance |
| Gross Pay (Earnings on Paystub) | Basic + HRA + Special Allowance | ₹17,35,110 | ₹1,44,593 | Gross Payslip Earnings |
| Employer EPF Contribution | Capped at ₹15,000 ceiling (12%) | ₹21,600 | ₹1,800 | Employer Retiral (Part of CTC) |
| Gratuity Provision | 4.81% of Basic Salary | ₹43,290 | ₹3,608 | Statutory Reserve (Part of CTC) |
| Total Cost to Company (CTC) | Gross Pay + Employer Retirals | ₹18,00,000 | ₹1,50,000 | Recruiter Quoted Package |
| Employee EPF Deduction | 12% statutory deduction | ₹21,600 | ₹1,800 | Deduction to EPFO Account |
| Professional Tax (PT) | State slab (KA, MH, TS, WB) | ₹2,400 | ₹200 | State Government Withholding |
| Income Tax (TDS - New Regime) | Calculated on ₹16,60,110 taxable | ₹1,95,554 | ₹16,296 | Monthly Income Tax Withholding |
| Net Monthly In-Hand Salary | Gross Pay − Deductions | ₹15,15,556 | ₹1,26,297 | Net Credited to Bank Account |
When an employer applies the standard capped EPF mechanism, your gross earnings equal ₹1,44,593 per month. Deducting ₹1,800 for your EPF, ₹200 for state professional tax, and ₹16,296 for monthly income tax yields an exact in-hand salary of ₹1,26,297 per month. You can verify your personalized salary numbers instantly with our CTC to In-Hand Salary Calculator.
Entering the 30% Tax Slab Under the New Tax Regime
At 18 LPA, your taxable income crosses ₹15,00,000, bringing a portion of your compensation into the top 30% tax bracket. Let us examine the official legal calculation under the default New Tax Regime for FY 2026-27 (AY 2027-28):
- Gross Salary Earned: ₹17,35,110 (excluding employer retirals).
- Standard Deduction (Section 16 ia): Flat ₹75,000 for salaried individuals.
- Net Taxable Income: ₹17,35,110 − ₹75,000 = ₹16,60,110.
- Applying the New Tax Regime Slabs:
- ₹0 to ₹3,00,000 @ 0% = ₹0
- ₹3,00,001 to ₹7,00,000 (₹4,00,000 band) @ 5% = ₹20,000
- ₹7,00,001 to ₹10,00,000 (₹3,00,000 band) @ 10% = ₹30,000
- ₹10,00,001 to ₹12,00,000 (₹2,00,000 band) @ 15% = ₹30,000
- ₹12,00,001 to ₹15,00,000 (₹3,00,000 band) @ 20% = ₹60,000
- Above ₹15,00,000: (₹16,60,110 − ₹15,00,000 = ₹1,60,110) @ 30% = ₹48,033
- Total Base Tax Computed: ₹20,000 + ₹30,000 + ₹30,000 + ₹60,000 + ₹48,033 = ₹1,88,033.
- Health and Education Cess (4%): 4% of ₹1,88,033 = ₹7,521.32.
- Final Annual Tax Payable: ₹1,88,033 + ₹7,521.32 = ₹1,95,554 (Monthly TDS: ₹16,296).
Strategic Tax Optimization: Saving ₹65,000+ Annually
At 18 LPA, paying nearly ₹2 Lakhs in income tax is painful. How can senior professionals legally reduce this burden under the New Tax Regime?
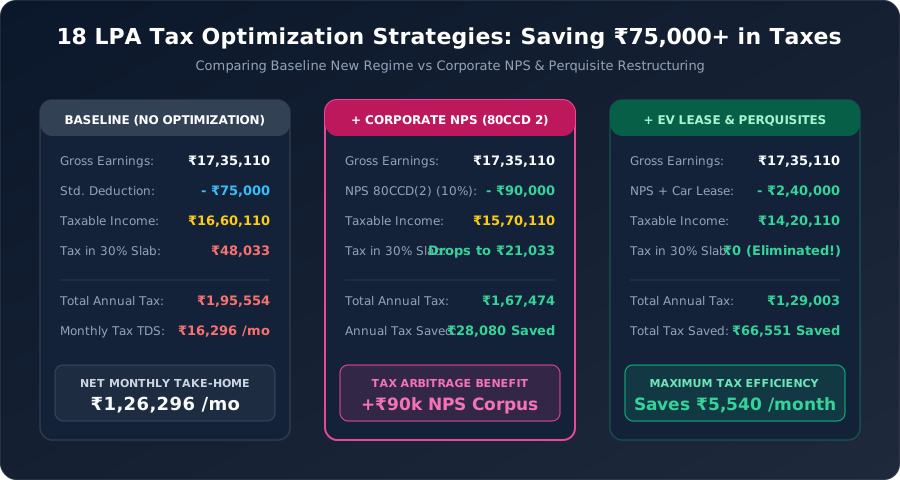 Figure 2: Comparing baseline New Regime taxation against Corporate NPS and EV lease perquisite optimization.
1. Corporate NPS under Section 80CCD(2)
Under Section 80CCD(2), employer contributions to your NPS account up to 14% of basic salary are 100% tax-deductible under the New Tax Regime!
On a ₹9,00,000 basic salary, allocating 10% (₹90,000/year, or ₹7,500/month) reduces taxable income from ₹16,60,110 to ₹15,70,110. Because this ₹90,000 deduction is carved out of your top 30% bracket, you immediately save 31.2% (including cess):
₹90,000 × 31.2% = ₹28,080 saved in direct cash tax!
2. Electric Vehicle (EV) Company Car Lease Scheme
Many modern tech firms and MNCs partner with leasing firms (such as LeasePlan or ORIX) to offer EV car lease programs. The monthly lease payment (e.g., ₹20,000/month) is deducted directly from your pre-tax Special Allowance bucket as a corporate perquisite. This knocks an additional ₹2,40,000 off your taxable income, saving over ₹50,000 in annual tax while financing your vehicle.
Capped EPF (₹1,800) vs Uncapped 12% (₹9,000)
At 18 LPA, your monthly basic salary is ₹75,000. This opens two distinct operational choices in corporate payroll:
| EPF Contribution Model | Monthly Employee PF | Monthly Employer PF | Total Monthly PF Saved | Net Monthly In-Hand |
|---|---|---|---|---|
| Statutory Capped PF (₹15,000 base) | ₹1,800 | ₹1,800 | ₹3,600 /mo | ₹1,26,297 |
| Uncapped PF (12% of actual ₹75,000 base) | ₹9,000 | ₹9,000 | ₹18,000 /mo | ₹1,18,297 |
The Compounding Advantage: Choosing the uncapped scheme reduces your immediate monthly take-home by ₹8,000. However, it directs a massive ₹18,000 every month into your sovereign-backed EPF account. At an annual interest rate of 8.25%, this additional saving builds over ₹13.8 Lakhs of tax-free retirement capital in just 5 years. Check your custom compounding with our EPF Calculator.
Gratuity Reserves on a ₹75,000 Basic Salary
Every 18 LPA offer letter typically budgets roughly ₹43,290 per year (₹3,608/month) under the heading of Gratuity. Under the Payment of Gratuity Act, 1972, this sum is not paid monthly. It represents a mandatory employer accrual payable when you separate from the company after completing 5 continuous years of service (or upon retirement or death).
The statutory formula for gratuity payout is:
Gratuity = (15 × Last Drawn Basic Salary × Tenure in Years) ÷ 26
If you work for 5 years at a final basic salary of ₹75,000, your statutory gratuity payout is (15 × 75,000 × 5) / 26 = ₹2,16,346. Check your future retiral payouts using our free Gratuity Calculator.
Professional Tax Variations Across Indian Metro Cities
Salaried professionals in India are subject to state-level Professional Tax (PT). For an 18 LPA package (monthly gross ~₹1,44,000), here is how your base location affects your take-home pay:
- Karnataka (Bengaluru): ₹200/month (Annual: ₹2,400). Monthly In-Hand: ~₹1,26,297.
- Maharashtra (Mumbai / Pune): ₹200/month for 11 months, ₹300 in February (Annual: ₹2,500). Monthly In-Hand: ~₹1,26,297 (₹1,26,197 in Feb).
- Telangana (Hyderabad): ₹200/month (Annual: ₹2,400). Monthly In-Hand: ~₹1,26,297.
- Tamil Nadu (Chennai): Levied half-yearly at ₹1,250 (Annual: ₹2,500, approx. ₹208/month). Monthly In-Hand: ~₹1,26,289.
- Delhi NCR & Haryana (Gurugram): No Professional Tax levied. Monthly In-Hand: ~₹1,26,497 (highest in India).
Building a ₹3.5 Crore Corpus on ₹1.26 Lakhs In-Hand
Taking home ₹1,26,000 per month grants comfortable luxury across Indian metro hubs while maintaining massive wealth-building capacity. A practical financial allocation for a senior professional earning ₹1,26,000 per month:
Rent (premium 3BHK flat), utilities, groceries, high-speed Wi-Fi, domestic staff, and vehicle maintenance.
Fine dining, international vacations, gadgets, entertainment, and executive fitness/club memberships.
Automated monthly SIP into diversified equity index funds and emergency contingency reserves.
If you invest ₹45,000 every month in an equity mutual fund SIP delivering an annualized compound return of 12%, your investment trajectory unfolds as follows:
- After 5 Years: Over ₹37.1 Lakhs (invested: ₹27 Lakhs).
- After 10 Years: Over ₹1.04 Crore (crosses the Crore milestone!).
- After 15 Years: Over ₹2.27 Crores (surpasses the ₹2 Crore mark!).
- After 18 Years: Crosses the ₹3.53 Crore Milestone!
Model your customized SIP accumulation milestones with our SIP Calculator.
Next Career Move: Breaking Through to 25 LPA+ Leadership Roles
When transitioning from 18 LPA to an engineering director, vice president, or principal architect role, professionals typically target a 35% to 50% increment, pushing compensation into the 24 LPA to 27 LPA bracket.
A 40% increment elevates your package to ₹25.2 LPA, lifting your monthly in-hand from ₹1,26,297 to roughly ₹1,68,000. You can simulate multiple offer letters and calculate your exact hike percentage using our free Salary Hike Calculator.
Frequently Asked Questions
What is the exact monthly take-home salary for 18 LPA in India?
On an 18 LPA CTC package, your monthly take-home pay is typically ₹1,26,297 if your employer caps EPF at ₹1,800 per month. If your employer calculates an uncapped 12% EPF on your actual basic salary, monthly in-hand is roughly ₹1,18,297.
Why does 18 LPA trigger the 30% income tax slab?
Under the New Tax Regime for FY 2026-27, taxable income exceeding ₹15,00,000 is taxed at the maximum marginal rate of 30%. At 18 LPA, your gross taxable income after standard deduction is ₹16,60,110. The top ₹1,60,110 portion is taxed at 30% plus 4% cess.
How can I reduce tax on an 18 LPA salary using Corporate NPS?
Under Section 80CCD(2), employer contributions to your NPS account up to 14% of basic salary are completely tax-deductible under the New Tax Regime. Contributing 10% of a ₹9 Lakh basic (₹90,000/year) saves roughly ₹28,080 in tax because that entire deduction comes out of your 30% tax bracket.
Can I take a home loan on an 18 LPA salary?
Yes. With a stable monthly net take-home salary of over ₹1,26,000, leading banks typically approve home loans of ₹80 Lakhs to ₹1.05 Crores, and luxury car loans at affordable monthly EMIs. You can calculate your exact loan EMIs using our EMI Calculator.
Why does my employer deduct gratuity from my CTC?
Under the Payment of Gratuity Act, 1972, gratuity is payable after completing 5 continuous years of service. Companies budget for this statutory liability by allocating 4.81% of your basic salary (approx. ₹3,608/month) within your annual CTC package structure.
Is filing an Income Tax Return mandatory for 18 LPA?
Yes, filing ITR-1 or ITR-2 is mandatory under Section 139(1) of the Income Tax Act because your total gross income exceeds the basic exemption limit. Filing is also essential for maintaining financial compliance and securing easy loan approvals.